
Aetna Florida Timely Filing Limit: Which Deadline Applies to Your Claim in 2026
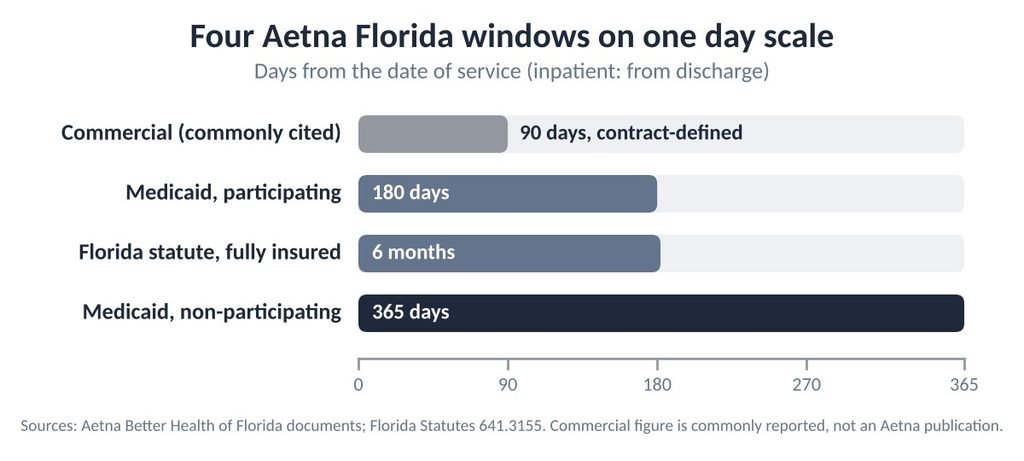
The Aetna Florida timely filing limit depends on the member’s plan. Aetna Better Health of Florida, the Medicaid plan, publishes 180 days from the date of service for participating providers. Florida law gives fully insured plans a six-month provider filing window. Commercial and Medicare Advantage limits come from your Aetna participation agreement.
Start with one question before you count any days: which Aetna product is on the card? Four different rulebooks sit behind the Aetna name in Florida, and a deadline copied from the wrong one is how clean claims end up denied. This guide explains the Aetna Florida timely filing limit product by product, adds the Florida statutes that sit underneath, runs four calculations and ends with a self-assessment checklist.
Aetna Florida deadlines at a glance
| Metric | Practical target/range | Review frequency | Source type |
| Aetna Better Health of Florida, participating providers | 180 days from service (inpatient: from discharge) | Each plan update | A |
| Aetna Better Health of Florida, non-participating providers | 365 days from service or discharge (2019 and 2023 plan documents) | Each plan update | A |
| Aetna Better Health of Florida, plan as secondary payer | 90 calendar days after the primary payer’s final determination | Per claim | A |
| Aetna Better Health of Florida, Medicare crossover | 36 months from the original Medicare submission | Per claim | A |
| Florida provider claim window, fully insured plans | 6 months after discharge or outpatient service | Annually | A |
| Aetna claim-payment dispute, Florida licensed practitioners | 12 months; facilities excluded; default is 180 days | Each Aetna update | A |
| Commercial, Medicare Advantage | Set by your participation agreement; 90 days is commonly cited for in-network commercial | At each contract renewal | C |
| Claim submission turnaround | Within 30 days of service for 95% or more of claims | Weekly | C |
Source types: A = published government or payer source (Florida Statutes, Aetna web pages and documents). B = named benchmarking data provider (none used). C = commonly reported across industry sources or a practical planning target. D = survey or study data (none used). Confirm against your contract and the current Aetna documents.
Start with the card: four Aetna products, four rulebooks
Aetna sells commercial, Medicare Advantage and Medicaid coverage in Florida, so the same logo can mean different filing windows. The table shows what Aetna publishes and where the published answer stops. It is a decision aid, so find the row for your claim and then confirm it in your contract.
| Aetna product | Initial claim window | What controls the answer |
| Aetna Better Health of Florida (Medicaid) | 180 days participating; 365 days non-participating | Published plan pages and training documents |
| Commercial, fully insured | Contract-defined; Florida’s six-month provider window applies underneath | Participation agreement and Florida Statutes |
| Commercial, self-funded employer plan | Contract-defined | Participation agreement and plan terms; state prompt-pay law may not reach these plans |
| Medicare Advantage | Contract-defined; industry guides disagree on the default | Participation agreement and CMS rules |
Source: Aetna Better Health of Florida claims page and documents; Florida Statutes 641.3155 and 627.6131. Commercial and Medicare Advantage rows rely on contract language that Aetna does not publish on the pages reviewed.
In billing audits, a common pattern is that offices keep one Aetna deadline in their billing system and apply it to every card. Build the deadline from the product, which usually shows on the card or the eligibility response, not from the payer name.
What Aetna Better Health of Florida publishes
The Medicaid plan gives the clearest day counts. Its claims page states that providers must file within 180 days of the date services were provided, unless a contractual exception applies. For inpatient claims, the date of service is the discharge date. You can read the wording on the Aetna Better Health of Florida claims page.
Plan documents add the rest of the picture. A Florida provider document (FL-19-08-03) lists 365 days for non-participating providers, 90 calendar days when the plan is secondary and 36 months for a Medicare crossover. A claims training deck (FL-19-02-15, revised February 2023) repeats those figures. Both documents say provider agreements control when they differ.
Which corrected-claim rule is current?
The current claims page says providers have 180 days from the paid date to resubmit a revised version of a processed claim. The older training deck and the 2019 document count corrected claims from the date of service or discharge. Where sources conflict, use the shorter window until Aetna confirms in writing, and keep that confirmation with the account.
The 2019 document also sets appeal windows: medical necessity appeals within 60 days of the adverse notice, and billing disputes within 90 days of the remittance for participating providers. Those figures are several years old, so verify them on the current appeals page before relying on them.
Florida law sets a six-month floor for fully insured plans
Florida statutes give providers a six-month window to send claims to fully insured health plans. Section 641.3155, the prompt payment statute for health maintenance organizations, states that provider claims must be mailed or electronically transferred within six months after discharge or the outpatient service date. The provider must also have received the correct name and address of the patient’s plan.
Section 627.6131 uses the same six-month language for health insurers and gives a secondary insurer 90 days after the primary’s final determination. These sections govern fully insured coverage. Self-funded employer plans generally fall under federal law, so the deadline in the contract is the safer guide there.
| Florida rule | What the statute says | What it means for billing |
| Provider filing window | 6 months from discharge or outpatient service | Treat six months as the outer limit, not the goal |
| Secondary claims | 90 days after the primary’s final determination | Date-stamp every primary EOB |
| Electronic claim payment | HMO pays within 20 days; insurer pays within 20 days or notifies the provider | Follow up at day 21, not day 91 |
| Paper claim payment | Pay or notify within 40 days | Paper claims slow every clock |
| Retroactive denial for ineligibility | Not allowed more than 1 year after payment | Keep payment dates on the account |
Source: Florida Statutes 641.3155 and 627.6131. These summarize the sections as published on the Florida Senate site; confirm current text before relying on a specific subsection.
Whether a shorter contract window can override the statute is a legal question, and this article does not answer it. The practical rule is to meet the shorter of the contract and the statute, and to ask your attorney before you rely on the longer one.
Four calculations to run before a claim ages out
Four short calculations convert the rules into dates and rates. Run the first three on any claim older than 60 days, and the fourth every month. Each starts with the formula, then an illustrative scenario with real numbers that your team can copy into a spreadsheet.
Calculation 1: the Aetna Better Health of Florida outpatient deadline
Formula: deadline = date of service + 180 days for a participating provider.
Illustrative scenario (not an actual client record): an office visit occurs on July 20, 2026, and the deadline is January 16, 2027. On October 16, 2026, 88 days have passed and 92 remain. A claim still unbilled at day 88 needs an owner and a date.
Calculation 2: the inpatient deadline
Formula: deadline = discharge date + 180 days, because the clock for inpatient claims runs from discharge.
Illustrative scenario (not an actual client record): a patient is discharged on September 5, 2026. The deadline is March 4, 2027. On October 16, 2026, 41 days have passed and 139 remain. Counting from admission instead would shorten the window and send the claim out too early.
Calculation 3: the contract window versus the statute
Formula: working deadline = the earlier of the contract window and the six-month statutory window.
Illustrative scenario (not an actual client record): an outpatient service occurs on April 25, 2026, under a fully insured plan. A hypothetical 90-day contract window ended July 24, 2026, and the six-month statutory window ends October 25, 2026. On October 16, 2026, nine statutory days remain. If the contract does say 90 days, the claim is already at risk, so confirm the contract before you treat October 25 as safe.
Calculation 4: the on-time submission rate
Formula: on-time rate = claims submitted within 30 days of service ÷ total claims × 100.
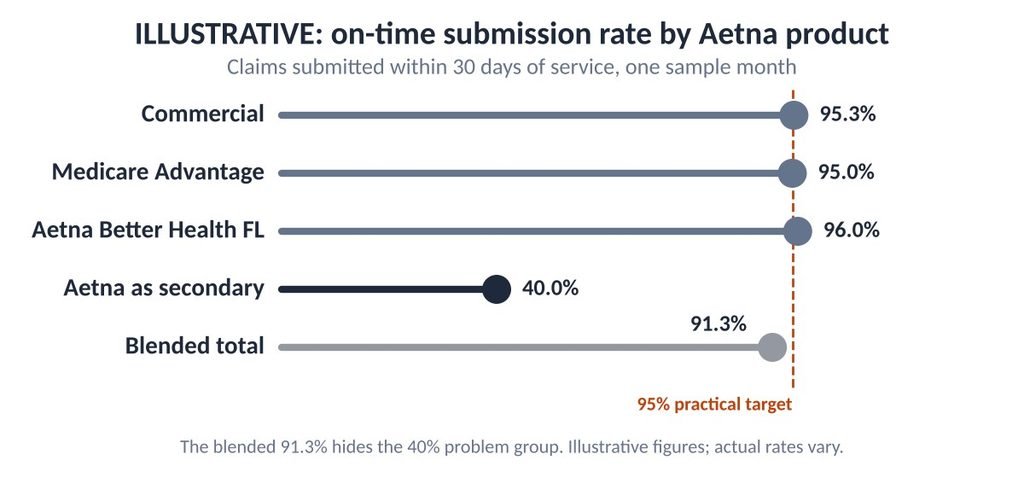
Illustrative scenario (not an actual client record): one month of Aetna claims, split by product, shown next to the blended total that most dashboards report.
| Aetna product (Illustrative) | Claims | Submitted within 30 days | On-time rate |
| Commercial | 150 | 143 | 95.3% |
| Medicare Advantage | 120 | 114 | 95.0% |
| Aetna Better Health of Florida | 100 | 96 | 96.0% |
| Aetna as secondary payer | 30 | 12 | 40.0% |
| Blended total | 400 | 365 | 91.3% |
Illustrative figures; actual rates vary by practice, specialty and plan mix.
The blended 91.3% sits near a 95% practical target. The secondary-payer line at 40% is the real problem, and the combined number hides it. Review each product and each billing sequence separately whenever one group waits on another payer before it can bill.
Reading your numbers without fooling yourself
Compare like for like. Commercial, Medicare Advantage and Medicaid claims run on different rulebooks, and secondary claims run on a different trigger, so each deserves its own row. One missed benchmark is a signal to investigate, not a verdict on the billing operation.
When a rate falls below target, check three things first. Was the deadline built from the right product? Did the delay sit in registration, in coding or in waiting for another payer? Do the late claims share a trigger, such as a primary payer’s remittance? A cluster of late claims usually traces to one cause, such as a staffing gap or a stalled eligibility batch.
When the contract is silent: a decision path for Aetna claims
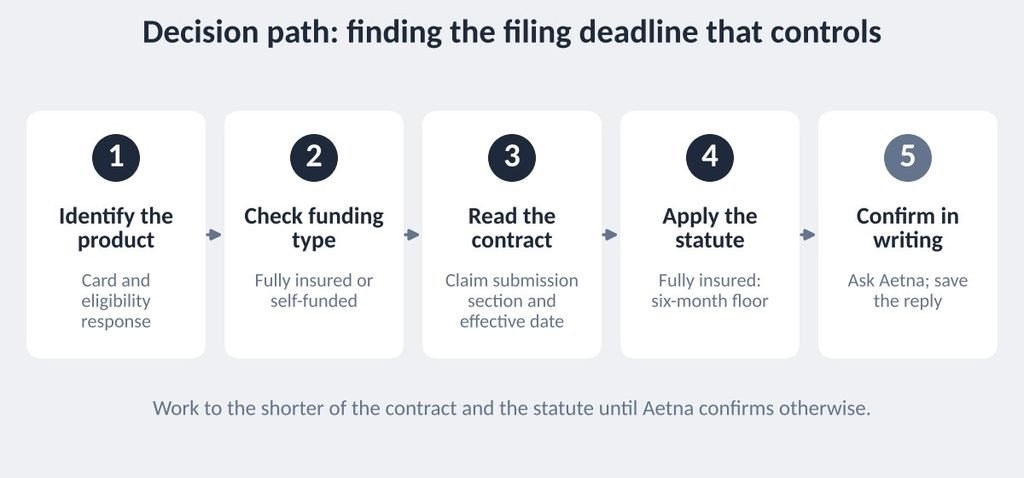
Contracts do not always name the deadline, and portals do not always say which product applies. When you cannot find the answer, follow the path below before the claim ages, and keep a note of each step on the account:
- Confirm the product from the card and the eligibility response, and note whether the plan is fully insured or self-funded.
- Pull the contract section on claim submission, and write the window beside the product in your deadline table.
- If the contract is silent and the plan is fully insured, work to the shorter of the statute and any plan page that applies.
- Ask Aetna provider services for the window in writing, and file the response with the account.
- Submit as early as the claim is clean, and save the clearinghouse acceptance and Aetna’s acknowledgment.
In billing audits, a common pattern is that the contract copy in the billing office is an old amendment. Check the effective date on the contract in use before you rely on a window. For state-by-state contrast, read our guides to Aetna Texas and Aetna California, where Aetna rules differ by state.
How Aetna disputes work in Florida
Aetna’s provider appeals page sets a default: in the absence of a state exception, Aetna’s 180-day dispute filing standard applies. The page lists a Florida exception of 12 months for initial claim-payment disputes. It covers participating and nonparticipating licensed physicians and physician assistants, plus osteopathic physicians, chiropractors, podiatrists and dentists, and it does not apply to facilities. Aetna states the exceptions apply to fully insured plans only, per its provider appeals page.
A dispute window is not a filing window. A claim that was never filed on time does not become timely because a dispute window is open, and our guide to timely filing versus appeal filing limits explains the difference. For secondary claims, see our guide to secondary claim timely filing deadlines.
Habits that keep Aetna claims on time in Florida
A workable routine has six steps, each tied to a trigger such as a new patient, a primary payer’s remittance or a denial, and the list below shows the order most offices can adopt:
- Record the Aetna product and funding type at registration, and add the window to your deadline table.
- Submit within 30 days of service as a practical target, and save the acknowledgment; the guide to payer-specific claim submission rules shows how to keep one row per payer.
- Flag unpaid claims at 90, 180 and 270 days from service using the method in tracking unpaid claims across payers.
- Date-stamp every primary payer remittance on the day it arrives, because secondary windows start there.
- Send corrected claims using the shorter of the plan page and the contract; our guide to corrected claim deadlines by payer compares the options.
- Review denials monthly by product, and refer balances past 270 days to A/R management support when the in-house team cannot clear them.
Our walkthrough on how to track timely filing deadlines shows a spreadsheet layout you can adapt. If the same patient also has Medicare, the Medicare 12-month rule guide covers that coverage, and our Medicaid Florida timely filing guide covers the state program.
How long until the routine shows results?
These are general planning ranges, not guarantees. A deadline table and a daily worklist often reduce last-minute submissions within two to four weeks. Denial trends take longer to read. Three to six months of data is a reasonable horizon, and a full year shows whether secondary and corrected claims are handled on time.
Mistakes that turn good Aetna claims into late denials
- Using one Aetna deadline for every card. Build the deadline from the product and the funding type.
- Counting inpatient claims from admission. Aetna Better Health of Florida counts from discharge.
- Treating a competitor’s table as the contract. Several guides cite 90 days for commercial claims with no Aetna source, so check your agreement.
- Missing the secondary window. Start the 90 days from the primary’s final determination.
- Assuming a dispute window reopens filing. Disputes and initial filing run on separate clocks.
- Ignoring conflicting sources. When two documents disagree, follow the shorter window and get written confirmation.
Quick summary
- The Aetna Florida timely filing limit depends on the product on the card.
- Aetna Better Health of Florida publishes 180 days for participating providers and 365 for non-participating.
- Florida law sets a six-month provider window for fully insured plans.
- Secondary claims run 90 days from the primary’s final determination for Aetna Better Health of Florida and under Florida statute.
- Commercial and Medicare Advantage limits come from your contract.
- A practical target is submission within 30 days of service for 95% or more of claims.
Self-assessment: is your Aetna Florida process safe?
Answer yes or no to each question below, then count your yes answers and compare the total with the three-tier scoring guide that follows the list of ten questions:
- Do you record the Aetna product and funding type at registration?
- Do you keep a written filing window for each Aetna product you bill?
- Do you know the filing language in your current Aetna participation agreement?
- Do 95% or more of claims go out within 30 days of service?
- Do you count inpatient claims from discharge?
- Do you date-stamp primary payer remittances for secondary claims?
- Do you flag unpaid claims at 90, 180 and 270 days?
- Do you keep clearinghouse acceptances and Aetna acknowledgments?
- Do you track on-time rates separately by product and by billing sequence?
- Do you review late-filing denials monthly?
Scoring guide: 9 to 10 yes answers suggests a well-controlled process, so review it quarterly. 6 to 8 yes answers suggests gaps; fix the “no” items first, starting with questions 1 and 3. 0 to 5 yes answers suggests high exposure to late-filing denials and a good moment for an outside review.
When outside billing help makes sense
Outside support is worth considering when the in-house approach has reached its limits. These five signals suggest that point has arrived for a Florida practice billing several Aetna products:
- Late-filing denials appear on Aetna claims more than one month in a row.
- Nobody can state the filing window for each Aetna product the practice bills.
- Primary payer remittances are not date-stamped, so secondary claims go out late.
- The contract copy in the billing office is old or unreviewed.
- Deadline tracking depends on one person’s spreadsheet.
Look for a billing partner that keeps a written deadline table by payer and product and retains acknowledgments. It should also report on-time rates by product and calendar every secondary and corrected claim window. Transparent reporting and clear pricing matter as much as the deadlines.
EON MED SOLUTIONS is one example: a US-based team that delivers medical billing, coding, credentialing, denial management and A/R follow-up with transparent reporting and no hidden fees. Results vary by practice. You can review the EON MED SOLUTIONS billing, coding and RCM services to see how the work is organized.
Expert Opinion
The Aetna Florida timely filing limit is not one number. The firm published standards in this guide are the day counts on Aetna Better Health of Florida’s pages and documents and the six-month and 90-day provisions in Florida Statutes 641.3155 and 627.6131. Aetna’s 180-day dispute default and its Florida 12-month exception are firm as well. The 30-day submission goal, the 90, 180 and 270 day alerts and the 90-day commercial figure are practical or commonly reported targets.
The worked examples are illustrative scenarios, not client results. They show how to turn a rule into a date and how a blended rate can hide a 40% subgroup. Because Aetna and the plans update their pages and contracts, recheck the numbers each year.
The natural next question is which of your Aetna products has no written filing window today. If the answer is more than one, a team that reads contracts and tracks remittances daily can help; start with EON MED SOLUTIONS’ billing and RCM services.
Frequently asked questions
What is the Aetna Florida timely filing limit?
It depends on the product. Aetna Better Health of Florida publishes 180 days from service for participating providers and 365 for non-participating. Florida law gives fully insured plans a six-month provider window. Commercial and Medicare Advantage limits come from your participation agreement, so check the contract before you count days.
What is the Aetna Better Health of Florida timely filing limit?
The plan’s claims page says providers must file within 180 days of the date of service unless a contractual exception applies. Inpatient claims count from discharge. Plan documents list 365 days for non-participating providers and 90 days when the plan is secondary, so confirm the current edition.
What is a good claim submission turnaround for Aetna claims?
A practical target is submitting most claims within a few business days, with 95% or more out within 30 days of service. This is an industry planning target, not an Aetna requirement. Early filing keeps most of the window in reserve for rejections and corrections.
What is a good on-time submission rate for Aetna claims?
No published benchmark exists. A practical goal is 95% or more within 30 days of service, tracked separately for commercial, Medicare Advantage, Medicaid and secondary claims. When one group falls well below the blended rate, investigate that group’s trigger event first.
What is a good aging alert schedule for Aetna claims?
Many practices flag unpaid claims at 90, 180 and 270 days from the date of service. This is a planning schedule, not an Aetna rule. The 90-day flag matters most when your contract shortens the commercial window, so set the first alert before the shortest deadline you bill under.
Does Florida law override Aetna’s filing deadline?
Florida Statutes 641.3155 and 627.6131 set a six-month provider filing window for fully insured plans. Whether a shorter contract window overrides that is a legal question this article does not answer. Meet the shorter of the contract and the statute, and ask your attorney before relying on the longer one.
Sources and methodology
(a) Published standards and definitions from named bodies
- Florida Statutes section 641.3155, Prompt payment of claims (HMOs): Florida Senate.
- Florida Statutes section 627.6131, Payment of claims (health insurers): Florida Senate.
- Aetna Better Health of Florida, File or submit a claim: Aetna Better Health.
- Aetna Better Health of Florida document FL-19-08-03 (2019) and Billing and Claims Processing Provider Training FL-19-02-15, Rev. 02/23.
- Aetna provider appeals page with state exceptions (page metadata modified August 14, 2026): Aetna.
(b) Named benchmarking data providers. None used in this article.
(c) Practical or illustrative targets from general industry sources
- National Aetna timely filing guides (Muni Health, MedSole RCM, Billing Care Solutions) were reviewed for how competitors present Aetna rules. They disagree on commercial windows (90 days versus 90 to 120 days), cite no Aetna document for them and give little or no Florida-specific detail, so this article treats commercial limits as contract-defined.
- The 30-day submission goal, the 95% target and the 90, 180 and 270 day alerts are practical planning targets. All worked-example figures are illustrative.
(d) Survey or study data. None used in this article.
Methodology: the research reviewed the top results for the keyword, Florida Statutes, Aetna Better Health of Florida pages and documents, and Aetna’s provider appeals page in October 2026. Aetna’s commercial and Medicare Advantage provider manuals were not available for review, so the article does not state a commercial or Medicare Advantage day count as fact. Several plan documents are older or undated, and one source conflict on corrected claims is flagged in the text. Results vary by contract, product and funding type, and figures reflect information available at the time of research. Confirm every deadline against your current contract and Aetna documents.


