
Aetna California Timely Filing Limit: Claims & Disputes
The Aetna California timely filing limit for participating providers is set by the provider agreement, and 90 days from the date of service is commonly reported. Non-participating providers are widely reported to have 12 months. For fully insured plans, California law bars filing deadlines shorter than 90 days (contracted) or 180 days (non-contracted), and Aetna allows 365 days to dispute California HMO claim decisions and 180 days for traditional plans.
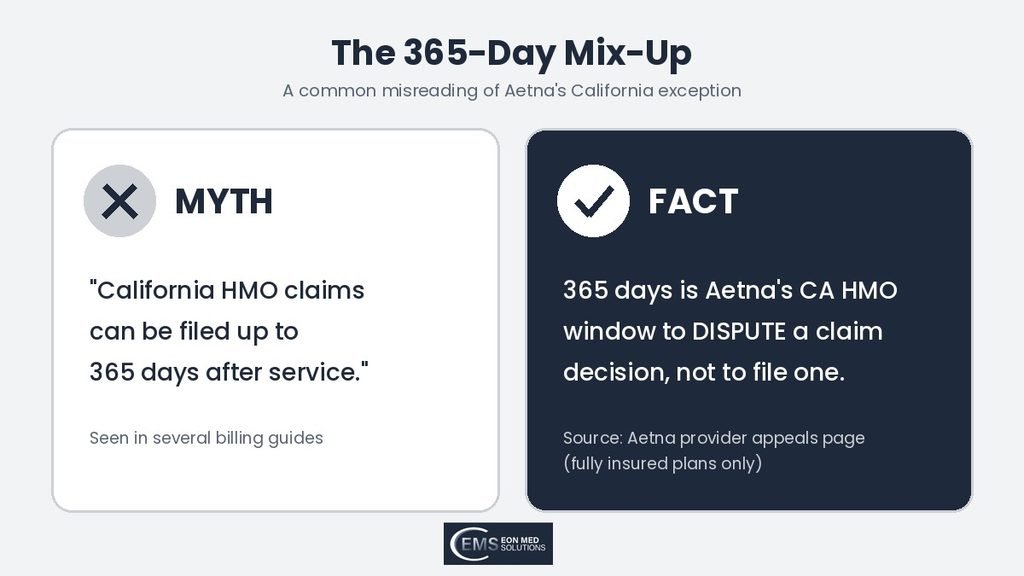
One popular billing guide says Aetna gives California HMO claims 365 days to be filed. It does not. That figure is Aetna’s window to dispute a claim decision, and the mix-up has cost practices real money. This guide separates the Aetna filing window from the dispute window and explains how product type and California law change both. You will also find worked date calculations, a product-by-product comparison, and illustrative internal targets. A nine-question readiness scorecard near the end shows where your Aetna workflow may be exposed.
Aetna California Deadlines in One Table
Keep this table beside whoever submits Aetna claims. Official rules come first; internal goals are labeled illustrative.
| Metric / Deadline | Practical Target or Rule | Review Frequency | Primary Source |
| Initial claim, participating provider | Per agreement; 90 days from DOS commonly reported | Weekly | Payer contract; industry-reported default |
| Initial claim, non-participating provider | 12 months from DOS (reported since 2022) | Monthly | Payer policy as reported by industry sources |
| California floor, contracted (fully insured) | No deadline under 90 days from DOS | Reference | Published standard: 28 CCR §1300.71(b)(1); Ins. Code §10133.66 |
| California floor, non-contracted (fully insured) | No deadline under 180 days from DOS | Reference | Published standard: 28 CCR §1300.71(b)(1); Ins. Code §10133.66 |
| Secondary claim floor (DMHC plans) | At least 90 days from primary decision | Per claim | Published standard: 28 CCR §1300.71(b)(1) |
| Claim-payment dispute, CA HMO | 365 days (fully insured, DOS on/after 1/1/2004) | Per denial | Payer policy: Aetna state exceptions page |
| Claim-payment dispute, CA traditional | 180 days (fully insured) | Per denial | Payer policy: Aetna state exceptions page |
| Aetna national dispute standard | 180 days where no state exception applies | Per denial | Payer policy: Aetna provider appeals page |
| Payment on complete claim | 30 calendar days (received on/after 1/1/2026) | Monthly | Published standard: AB 3275; DMHC APL 25-007 |
| Days to bill (internal) | 2–5 days from DOS | Weekly | Illustrative target |
| Claims accepted by day 45 (internal) | 99%+ | Monthly | Illustrative target |
Source labels: “Published standard” means California statute, regulation, or DMHC guidance sets the rule. “Payer policy” means Aetna publishes it. “Payer contract” and “industry-reported” mean the figure depends on your agreement and is widely cited, not guaranteed. “Illustrative target” means a practical internal goal; no agency or payer mandates it.
Breaking Down the Aetna California Timely Filing Limit
Participating providers: the contract controls
For participating providers, Aetna’s filing window lives in the provider agreement. Ninety days from the date of service is the figure most billing sources report, though some agreements allow longer. That makes Aetna one of the tighter commercial payers, so a missed batch or silent clearinghouse rejection can quickly become a lost claim. Pull your agreement, confirm the exact number, and load it into your practice management system. Do not rely on a blog post, including this one, for the number that governs your contract.
Non-participating providers: a longer but shrinking window
Industry sources widely report that Aetna reduced its window for non-participating providers from 27 months to 12 months starting January 1, 2022. For fully insured California plans, that 12-month window sits comfortably above the state’s 180-day floor. Out-of-network providers should still file early. A longer deadline does not help if eligibility problems or missing records surface in month eleven.
| Worked Example 1 — Participating vs. Non-Participating Dates Formula: Filing deadline = Date of service + applicable window Scenario: Service on May 4, 2026. • Participating provider with a 90-day agreement: claim due August 2, 2026. • Non-participating provider with a 12-month window: claim due May 4, 2027. |
Fully Insured, Self-Funded, or Medicare Advantage?
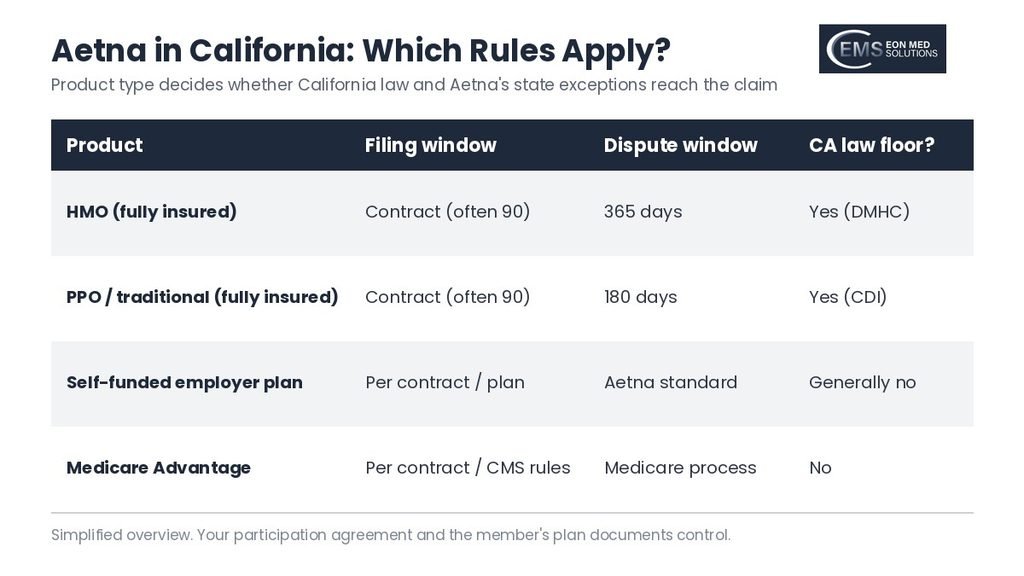
Aetna’s own provider appeals page notes that its state exceptions apply only to fully insured plans. That single sentence changes how California practices should read every Aetna rule. The product type on the member’s card decides which rulebook applies.
Fully insured HMO and PPO plans
Fully insured Aetna HMO plans in California fall under the Department of Managed Health Care (DMHC). Complete insured PPO and traditional products fall under the California Department of Insurance. Both regulators enforce claim filing floors, and both require a dispute process. For these members, 28 CCR §1300.71 and Insurance Code §10133.66 prevent filing deadlines shorter than 90 days for contracted providers or 180 days for non-contracted providers.
Self-funded employer plans
Aetna administers many self-funded employer plans, where the employer carries the risk. Those plans are govern mainly by federal ERISA rules and the plan document. California’s filing floors and AB 3275 payment rules generally do not reach them, and Aetna’s state exceptions do not apply. The member card may look identical to a fully insured card. Ask Aetna’s eligibility response or portal for the funding type, and record it on the account.
Medicare Advantage
Aetna Medicare Advantage claims follow federal Medicare Advantage rules and your agreement, not California commercial law. Industry sources report a 12-month window for non-contracted providers. Contracted windows vary, so check your Medicare Advantage agreement separately from your commercial one.
The 365-Day Myth: Filing Window vs. Dispute Window
What Aetna’s California exception actually says
Aetna publishes a table of state exceptions to its 180-day claim-payment dispute standard. For California HMO members with service dates on or after January 1, 2004, the dispute window is 365 days. For California traditional members, it is 180 days. Both apply to participating and non-participating providers, for fully insured plans only. Nothing in that table extends the time to file an original claim. A practice that waits eleven months to submit an HMO claim, relying on “365 days,” will likely be denied.
| Worked Example 2 — Dispute Deadlines by Product Formula: Dispute deadline = Date of Aetna’s claim decision + dispute window Scenario: Aetna decision dated September 15, 2026. • Fully insured HMO member (365 days): dispute due September 15, 2027. • Fully insured traditional member (180 days): dispute due March 14, 2027. |
Why the confusion spreads?
Several billing guides list “California HMO: 365 days” in their timely filing tables without explaining that the number comes from a dispute table. Copied across sites, the error starts to look like fact. The fix is simple: treat every number you read by asking which clock it belongs to. Is it filing, correction, secondary, or dispute? If your team struggles to keep these clocks straight across payers, structured denial management support can help.
Secondary Claims and California Payment Rules
When Aetna pays second?
For DMHC-regulated plans, California rules require at least 90 days to file a coordination of benefits claim after the primary payer’s payment, denial, or contest. Aetna’s own secondary rules may allow more, depending on product and contract. Record the primary EOB date on every secondary claim, since it becomes your proof of timeliness.
| Worked Example 3 — Secondary Claim Deadline Formula: Secondary deadline = Primary EOB date + 90 days (California floor for DMHC plans) Scenario: Primary EOB dated June 10, 2026 → Aetna secondary claim due by September 8, 2026, unless your contract allows longer. |
How fast Aetna must pay under AB 3275?
For complete claims received on or after January 1, 2026, state-regulated plans and insurers must pay, contest, or deny within 30 calendar days. DMHC guidance(4_1_2025).pdf) adds 15% annual interest on late payments for DMHC plans, plus a penalty if that interest is not paid automatically. Self-funded plans are generally outside these rules. Review late Aetna payments on fully insured products for missing interest.
Metrics That Reveal Aetna Filing Risk Early
Filing deadlines show when money disappears. Internal measures reveal the risk much sooner. The figures below are illustrative targets from general industry practice, not published Aetna benchmarks. Actual figures vary by specialty, product mix, and staffing, so verify against your own data where precision matters. Pair them with the broader medical billing KPIs your practice already watches.
| Metric (Illustrative) | Formula | Illustrative Target |
| Days to bill | Total days from service to submission ÷ claims submitted | 2–5 days |
| Accepted by day 45 | Aetna claims accepted by day 45 ÷ Aetna claims | 99%+ |
| Funding type captured | Aetna accounts with fully insured/self-funded flag ÷ Aetna accounts | 100% |
| Timely filing denial rate | Late-filing denials ÷ Aetna claims | 0% |
| Disputes filed by day 90 | Disputes filed within 90 days of decision ÷ disputes filed | 100% |
Illustrative: compiled from general industry practice, not a named benchmark. Actual figures vary.
| Worked Example 4 — Acceptance Rate and Revenue at Risk Acceptance formula: Claims accepted by day 45 ÷ total Aetna claims × 100. Scenario: 392 of 400 = 98%. Revenue at risk: 8 late claims × $165 average = $1,320 exposed if a 90-day agreement applies. |
How a blended rate can hide one Aetna product?
Illustrative scenario (not an actual client record): a family medicine group bills Aetna PPO, Aetna HMO through a delegated medical group, and Aetna Medicare Advantage. Its blended on-time rate is 96%. Split by product, PPO and Medicare Advantage sit near 99%, while the HMO line sits at 86%. Staff were sending HMO claims to Aetna instead of the delegated group. Aging balances like these deserve dedicated accounts receivable management attention.
| Aetna Product (Illustrative) | Claims | On Time | Rate |
| PPO (participating, 90-day) | 250 | 247 | 98.8% |
| HMO via delegated group | 150 | 129 | 86.0% |
| Medicare Advantage | 200 | 198 | 99.0% |
| Blended | 600 | 574 | 95.7% |
Reading Your Results Without Jumping to Conclusions
California floors and Aetna’s published dispute windows are fixed rules, not benchmarks. Internal targets are different and only make sense compared like-for-like. Compare the same Aetna product, a similar service mix, a comparable practice size, and the same reporting period. A practice with heavy HMO volume will look different from a PPO-focused specialty clinic. One missed target is a prompt to investigate, not a verdict on your staff. Trace the root cause before rewriting the workflow.
When to Expect Measurable Change?
These are general planning ranges, not guarantees for any specific practice. Backlog, product mix, and staffing will shift them.
| Fix | Partial Results | Fuller Results |
| Loading agreement-specific Aetna windows into billing software | 1–2 weeks | 1 month |
| Capturing funding type and delegated group at check-in | 2–4 weeks | 1–2 months |
| Same-day clearinghouse rejection review | 1–2 weeks | 1 month |
| Separate filing and dispute calendars | 1 month | 2–3 months |
| Late-payment interest review on fully insured claims | 1 month | 3 months |
Key Points at a Glance
- Participating Aetna providers follow their agreement; 90 days is the commonly reported window.
- Non-participating providers are widely reported to have 12 months from the date of service.
- California bars filing deadlines under 90 or 180 days for fully insured plans (published standard).
- The 365-day California HMO figure is Aetna’s dispute window, not a filing window; traditional plans get 180 days.
- Targets like 2–5 days to bill and 99%+ acceptance by day 45 are illustrative goals, not mandates.
Aetna California Readiness Scorecard: 9 Questions
Answer yes or no, then count your yes answers.
- Do you know the exact filing window in your current Aetna agreement?
- Do you record whether each Aetna member’s plan is fully insure or self-fund?
- Do you identify Aetna HMO members assigned to a delegated medical group?
- Is your average days to bill at or under five days?
- Were 99% or more of Aetna claims accepted by day 45 last month?
- Did you receive zero Aetna timely filing denials last quarter?
- Do you track filing deadlines and dispute deadlines on separate calendars?
- Do you record the primary EOB date on every Aetna secondary claim?
- Do you review on-time rates separately for each Aetna product?
8–9 yes: Strong control; keep reviewing monthly. 5–7 yes: Gaps exist; fix the “no” items this quarter. 0–4 yes: Revenue is likely slipping now; audit all Aetna claims older than 45 days this week.
Is It Time for a Billing Partner?
Many practices manage the Aetna California timely filing limit comfortably in-house. Others find the product types, delegated groups, and dispute rules hard to track. These signals suggest a closer look:
- Aetna timely filing denials appear more than once a quarter.
- Staff believe California HMO claims can be filed up to 365 days after service.
- No one records whether an Aetna plan is fully insured or self-funded.
- HMO claims regularly go to Aetna when they belong with a delegated group.
- Disputes are filed late or not at all because windows were never calendared.
Strong outside support should load contract-specific windows, flag funding type at eligibility, and track dispute dates separately from filing dates. Look for transparent reporting, HIPAA-compliant processes, and one named contact. Network status drives your window, so current credentialing matters too. EON MED SOLUTIONS is one example of that structure. Its US-based team provides end-to-end medical billing, coding, credentialing, denial management, and compliance support, with a dedicated agent per provider and no hidden fees. Results vary by practice and situation. You can see all services here.
Expert Opinion
The Aetna California timely filing limit depends on network status, funding type, and product. Participating providers follow their agreement, non-participating providers generally get longer, and California law sets floors for fully insured plans. The 365-day figure belongs to disputes, not original claims.
To be clear about sources: the 90-day and 180-day floors, the 90-day secondary minimum, and the AB 3275 payment rules are published California standards. The 365-day and 180-day California dispute windows are Aetna’s published payer policy. The 90-day participating and 12-month non-participating figures are widely reported defaults to confirm in your contract. Days to bill, the day-45 target, and improvement timelines are illustrative goals.
Frequently Asked Questions
What is the Aetna California timely filing limit?
For participating providers, it is set by the Aetna agreement, commonly 90 days from the date of service. Non-participating providers are widely reported to have 12 months, and California law sets 90-day and 180-day floors for fully insured plans.
Does Aetna allow 365 days to file California HMO claims?
No. Aetna’s 365-day California HMO rule is the window to dispute a claim decision. The original claim still follows your filing window.
What is a good days-to-bill target for Aetna claims?
Many practices aim for two to five days from service. This is an illustrative target, not an Aetna rule, but it protects a 90-day agreement.
What is a good acceptance rate for Aetna claims?
A practical goal is 99% or more of Aetna claims accepted by day 45. That illustrative target leaves room to fix rejections before any deadline.
How long do I have to dispute an Aetna claim in California?
For fully insured plans, Aetna lists 365 days for California HMO members and 180 days for traditional members. Other plans generally follow Aetna’s 180-day standard.
Do California filing rules apply to self-funded Aetna plans?
Generally no. Self-funded plans are governed mainly by ERISA and the plan document, and Aetna’s state exceptions apply only to fully insured plans.
What is the Aetna Medicare Advantage filing limit?
Contracted providers follow their Medicare Advantage agreement. Industry sources report 12 months for non-contracted providers.
What is a good way to avoid Aetna timely filing denials?
Verify funding type and delegated group at check-in, submit within days, and review rejection reports daily. Keep clearinghouse acceptance reports as proof of timely submission.
How quickly must Aetna pay a California claim in 2026?
For complete claims received on or after January 1, 2026, fully insured plans must pay, contest, or deny within 30 calendar days under AB 3275.
Source Categories and Research Limits
(a) Published standards: 28 CCR §1300.71; California Insurance Code §10133.66; Health and Safety Code §1371 as amended by AB 3275; and DMHC All Plan Letter 25-007. (b) Named benchmarking data providers: none used. Aetna’s dispute windows come from Aetna’s own provider appeals page, a payer policy rather than a benchmark. (c) Practical or illustrative targets: days to bill, day-45 acceptance, funding-type capture, and improvement timeframes, compiled from general industry practice. The 90-day participating and 12-month non-participating filing figures are widely reported industry defaults. (d) Survey data: none used. Actual results vary by practice and situation, and all figures reflect information available at the time of research in September 2026.
This article is educational and is not legal advice. Confirm deadlines in your Aetna agreement and current Aetna guidance. EON MED SOLUTIONS is not affiliated with Aetna.


