
UHC Florida Timely Filing Limit: 90 Days vs 6 Months (2026 Guide)
The UHC Florida timely filing limit depends on the plan type. UnitedHealthcare commercial contracts commonly set 90 days from the date of service, while Florida statutes tell providers to submit claims to fully insured plans within 6 months. Medicare Advantage and Community Plan windows follow separate contracts and manuals, so the member’s plan type decides the deadline.
Florida practices face two clocks on the same UnitedHealthcare claim: a contract number that is often 90 days and a state statute that says 6 months. Most pages on the UHC Florida timely filing limit repeat one flat figure and never mention the statute. This guide sorts the deadlines by plan type, explains how the two clocks interact, and closes with worked examples, a seven-step workflow and a self-assessment checklist.
A missed deadline rarely announces itself. It shows up weeks later as a CO-29 denial on a remittance, after the payment window has closed. The figures below reflect information available in October 2026. Florida statutes, UnitedHealthcare guides and Medicaid manuals change, so confirm anything that touches a live claim.
Which Numbers Belong on Your Florida UHC Deadline Sheet?
Eight numbers cover most UnitedHealthcare filing decisions in Florida, and only some of them come from statute. The table separates published rules from payer guidance and from practical targets, so your team can see which figures are fixed and which are internal habits. Check the source label on each row before loading a number into your practice management system.
Key numbers cheat sheet for UHC claims in Florida
| Metric | Practical target/range | Review frequency | Source type |
| Florida statutory filing deadline, fully insured plans | 6 months after discharge or date of service, once the provider has the correct insurer name and address | Annually | A |
| UHC commercial participating providers | At least 90 days from date of service, per Participation Agreement | At contract renewal | B |
| UHC commercial nonparticipating providers | Up to 180 days from date of service | At contract renewal | B |
| UHC Medicare Advantage, noncontracted providers | 365 days from the through date of service; contracted providers follow the agreement | At contract renewal | B |
| Secondary claim, fully insured plans | 90 days after the primary plan’s final determination | Monthly | A |
| Underpayment claim, licensed physicians and dentists | 12 months after the insurer’s payment, for services on or after January 1, 2026 | Annually | A |
| UHC Community Plan (Medicaid) | Set by the Florida manual and contract; confirm before filing | When manuals update | B |
| Internal submission target and alert | Within 5 business days of service; alert near day 55 on a 90-day window | Weekly | D |
Source labels: A = Florida statute (Fla. Stat. §627.6131 and §641.3155). B = payer-published guide, manual or policy; verify the wording in your own agreement. C = commonly reported across industry sources, not a verified mandate. D = practical target used by billing teams, not a mandate.
What Is the UHC Florida Timely Filing Limit for Each Plan Type?
The UHC Florida timely filing limit is a plan-type question: commercial contracts commonly use 90 days, Florida statute sets 6 months for fully insured plans, and Medicare Advantage and Community Plan claims follow their own documents. UnitedHealthcare’s 2026 Administrative Guide covers commercial, individual exchange and Medicare Advantage plans, and it sends providers to their Participation Agreement for filing time.
Illustrative summary: UHC filing windows by Florida plan type (compiled from named sources; actual windows vary by contract)
| Plan type | Commonly cited window | What controls it | Confidence |
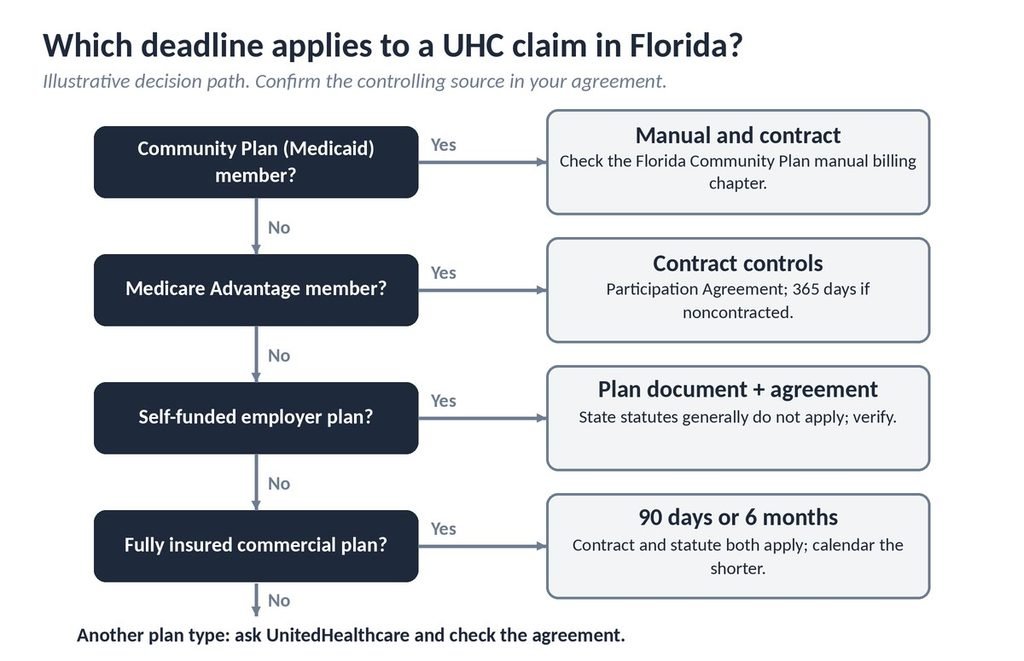
| Fully insured commercial (HMO or insurer product) | 90 days under many contracts; 6 months under statute | Agreement and Florida statute | Contract and statute both apply; confirm in writing |
| Self-funded employer plan | Plan document and agreement | Plan document | Generally outside state statute; verify |
| Medicare Advantage, contracted | Per Participation Agreement | Agreement | Verify in contract |
| Medicare Advantage, noncontracted | 365 days from through date of service | UnitedHealthcare guide supplement | Reported in 2026 guide summaries |
| UHC Community Plan (Medicaid) | Manual and contract set it | Florida Community Plan manual | Could not confirm a single figure |
| Original Medicare (not UHC) | 12 months | Federal rule | Published standard |
Fully insured commercial plans
Participating providers typically get at least 90 days under UnitedHealthcare’s commercial language, and nonparticipating providers up to 180 days, according to summaries of the 2026 guide. Florida law separately says a provider must submit a claim to the primary insurer within 6 months of discharge or the date of service. Florida provides parallel provisions for HMO products. Both numbers matter, and the next section explains why neither can be ignored when you set a working deadline.
Self-funded employer plans
UnitedHealthcare often administers plans funded by employers. State insurance statutes generally do not govern those self-funded plans, so the plan document and your agreement set the deadline. Do not assume the Florida 6-month rule applies. Ask the plan or check the member’s benefit documents when the card does not identify the funding type.
Medicare Advantage
Contracted providers follow their Participation Agreement. Noncontracted providers receive 365 days from the through date of service, according to 2026 guide summaries. Original Medicare keeps its own 12-month rule, covered in our Medicare timely filing limit guide, and is not governed by UnitedHealthcare’s contract windows.
UnitedHealthcare Community Plan (Medicaid)
Florida’s Medicaid managed care claims follow the plan contract and the UnitedHealthcare Community Plan Florida care provider manual. The excerpts reviewed did not show one filing figure, so check the manual’s billing chapter before calendaring. Our Florida Medicaid timely filing guide covers fee-for-service and managed care windows.
Does Florida’s Six-Month Statute Override a 90-Day UHC Contract?
Not clearly. Florida statute says providers must submit claims to the primary insurer within 6 months, while many UnitedHealthcare commercial agreements use 90 days, and the sources reviewed do not resolve which controls when the two differ. The safe working rule is to calendar the shorter contract number and treat the statute as a possible fallback, not a plan.
Most competing pages list “UHC: 90 days” and never mention Florida Statute 627.6131, which sets the 6-month deadline for insurer products. Section 641.3155 repeats it for HMOs. A provider who files on day 120 and wins an appeal on statute alone is taking a risk that none of the sources reviewed endorse.
In billing audits, a common pattern is a Florida practice that learns about the 6-month statute and quietly stretches its internal deadline to match. That works only if every contract agrees. When the Participation Agreement states 90 days, ask UnitedHealthcare in writing which deadline applies to your plan line, and consider asking a healthcare attorney before relying on the longer number.
When Does the Florida Filing Clock Start, Restart or Stretch?
The clock normally starts on the date of service, but facility, secondary, corrected and underpayment claims each follow a different start point. Identify the plan type first, then the event that begins the count, because a discharge date or a primary determination can move a deadline by weeks.
Facility and inpatient claims
Florida’s statute starts the 6 months at discharge for inpatient services and at the date of service for outpatient services. The statute also ties the clock to the provider receiving the correct name and address of the patient’s insurer. When registration data was wrong, document the date you received corrected insurance information.
Secondary claims
For fully insured plans, a claim to the secondary payer must be mailed or electronically transferred within 90 days after the primary payer’s final determination. Store the primary remittance date on every secondary claim, and see our secondary claim timely filing guide for sequencing rules.
Corrected claims
UnitedHealthcare’s guide, as summarized by third parties, says the filing days in your agreement also apply to corrected claims, counted from the date of service. Many websites claim a separate 180-day window from the remittance, which was not confirmed in the UnitedHealthcare language reviewed. Submit corrections inside the original window; our corrected claim deadlines by payer guide compares payers.
Underpayment claims
A 2025 Florida law added a 12-month limit for underpayment claims by licensed physicians, osteopaths, chiropractors, podiatrists and dentists. The legislature’s note says it applies to claims for services provided on or after January 1, 2026. The clock starts at the insurer’s payment, so review remittances for short payments within months, not years.
How Do You Calculate a UHC Deadline in Florida?
A deadline equals the clock start date plus the filing limit, and your billing system should calculate it rather than staff counting by hand. Each example below uses a different formula, so your team can copy the logic into a spreadsheet or a practice management rule.
Worked example 1: two clocks on one claim
Illustrative scenario (not an actual client record): A Florida practice sees a patient on a fully insured UHC commercial plan on August 24, 2026. Formula: deadline = date of service + filing limit. With a 90-day contract term, the deadline is Sunday, November 22, 2026, so the practical hard stop is Friday, November 20. The 6-month statutory date would be Wednesday, February 24, 2027. The working deadline is the earlier one.
Worked example 2: a secondary claim
Illustrative scenario (not an actual client record): The primary payer’s final determination for a different patient is dated September 28, 2026, and UHC is secondary on a fully insured plan. Formula: secondary deadline = primary determination date + 90 days. September 28 plus 90 days is Sunday, December 27, 2026. December 25 falls on a Friday, so the practical hard stop is Thursday, December 24.
Worked example 3: how a blended average hides a problem
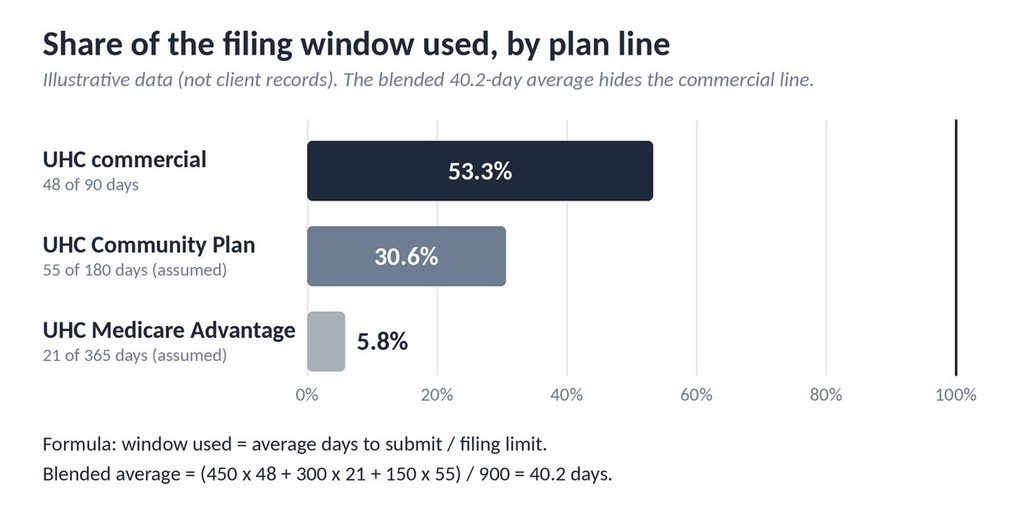
Illustrative scenario (not an actual client record): A practice reviews average days from service to submission across three UHC plan lines. Formula: window used = average days to submit ÷ filing limit. The figures are invented for teaching and contain no client information, and the limits for the second and third lines are assumptions for the example.
Illustrative data: average days to submit by plan line (actual figures vary)
| Plan line | Claims | Average days to submit | Filing limit used | Window used |
| UHC commercial | 450 | 48 | 90 | 53.3% |
| UHC Medicare Advantage | 300 | 21 | 365 (assumed) | 5.8% |
| UHC Community Plan | 150 | 55 | 180 (assumed) | 30.6% |
| Blended | 900 | 40.2 | n/a | n/a |
The blended average is (450 × 48 + 300 × 21 + 150 × 55) ÷ 900 = 40.2 days, which looks comfortable against a 90-day limit. The commercial line already uses 53.3 percent of its window on average, so slower claims in that line are at risk. Track the share of claims submitted after day 60 for each plan line, not just the overall mean.
Which Seven Steps Keep Florida UHC Claims Inside the Window?
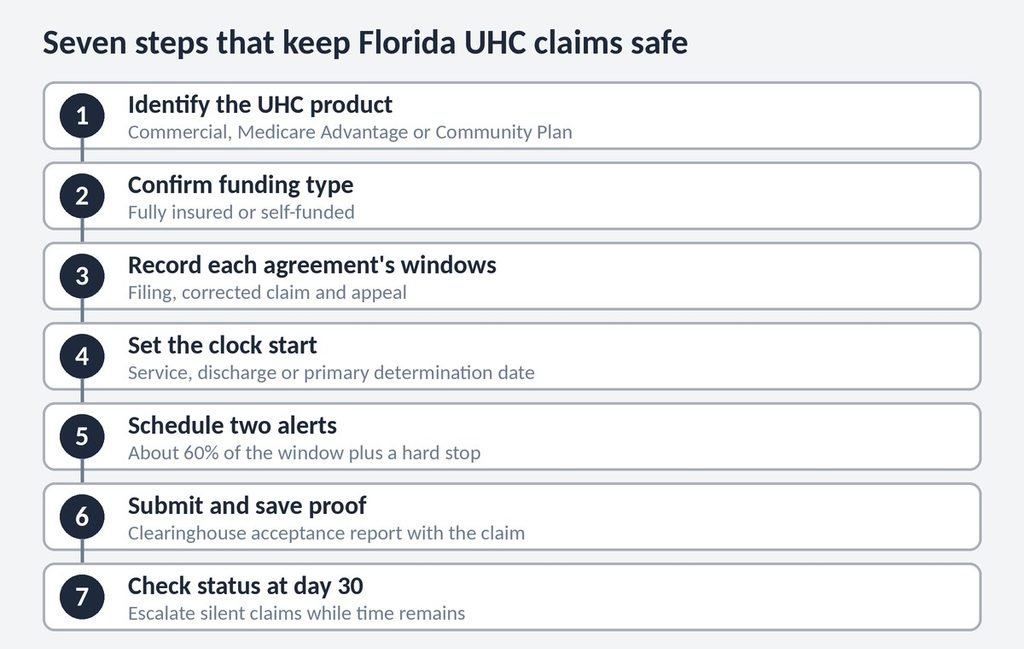
Seven steps keep claims inside the window when your practice sees commercial, Medicare Advantage and Community Plan patients. They work in order, and each step produces a date or a document that a later step relies on. Skip none when claim volume is high.
- Identify the UnitedHealthcare product at registration. Scan both sides of the card and separate commercial, Medicare Advantage and Community Plan members.
- Confirm whether the plan is fully insured or self-funded when the card does not say. Use the UnitedHealthcare Provider Portal or Provider Services.
- Record the filing, corrected-claim and appeal windows from your Participation Agreement for each product in your practice management system.
- Set the clock start: date of service, discharge date or primary determination date for secondary claims.
- Schedule two alerts: an internal alert near 60 percent of the window and a hard stop two business days before the deadline.
- Submit electronically and save the clearinghouse acceptance report with the claim record. Our electronic claims submission tips cover clearinghouse setup.
- Check claim status around day 30 and escalate silent claims while time remains to refile.
Weekly worklists do most of the protecting, because a dated queue catches a stalled claim long before the deadline does. Our step-by-step guide to tracking timely filing deadlines covers worklist design. When the worklist outgrows the front-office team, EON MED SOLUTIONS handles this follow-up inside its A/R management service.
What Proves a Florida UHC Claim Was Filed On Time?
The best proof of timely filing is a clearinghouse or payer acceptance report dated inside the window, because UnitedHealthcare provider guidance states that a submission report alone is not proof for electronic claims. Florida’s insurer prompt-pay statute also requires electronic acknowledgment of a claim within 24 hours after the start of the next business day.
Keep both records together: the acceptance report from your clearinghouse and the insurer’s acknowledgment, filed under the claim number. For mailed claims, the statute treats the claim as submitted on the date it is mailed, so a mail log or tracking record matters just as much for paper submissions.
In denial work, a common pattern is that the acceptance report existed on the day of submission but was never attached to the claim record. The appeal clock is separate from the filing clock, so read the denial on the day it arrives; our timely filing limit versus appeal filing limit guide explains the difference. Practices that want help assembling appeal files can review EON MED SOLUTIONS’ denial management service.
Where Do Florida Practices Lose UHC Revenue to the Clock?
Most losses trace to workflow errors, not payer surprises. Each fix below applies under a stated condition, so start with the ones that match your payer mix and your monthly claim volume, and add the rest as your team’s capacity allows over the following quarter.
- Using one UHC number for every product. When your payer mix includes commercial, Medicare Advantage and Community Plan, set the limit per plan line.
- Stretching the deadline to the statute. When your agreement says 90 days, calendar 90 days unless UnitedHealthcare confirms otherwise in writing.
- Counting from the day the claim was sent. When staff count from submission, recount from the date of service, discharge date or primary determination date.
- Treating a rejection as a filed claim. A claim rejected at the front end was not accepted. When a rejection report appears, fix and resubmit the same day.
- Leaving secondary claims unowned. When secondary volume is more than occasional, assign one person to track the primary determination dates.
- Skipping front-end checks. Eligibility errors delay submission, so review our medical billing KPIs guide when days to submit creep up.
How Should You Read These Numbers, and How Fast Can Practices Improve?
Compare like for like: judge commercial lag against commercial, and Community Plan lag against Community Plan. One late claim is a signal to investigate the workflow, not a verdict on the team. A single month’s average also hides seasonal swings, so look at three months before changing staffing.
Planning ranges help set expectations. Alert rules, worklists and plan-line limits can often be in place within 30 to 60 days. Contract abstraction, rejection cleanup and consistent proof storage commonly take 90 to 180 days. These are general planning ranges, not guarantees, and they vary with claim volume and software. UnitedHealthcare rules also differ by state, as our UHC California timely filing guide shows.
Quick Summary
- The UHC Florida timely filing limit depends on plan type; 90 days is a common commercial contract term.
- Florida statute tells providers to file with fully insured primary plans within 6 months, but the sources reviewed do not say it overrides a shorter contract.
- Secondary claims have a 90-day statutory window from the primary plan’s final determination.
- Medicare Advantage and Community Plan claims follow contracts and manuals, not the commercial number.
- A practical target is submission within 5 business days, with an alert near day 55 on a 90-day window.
- Acceptance reports, not submission reports, are the proof that wins disputes.
Is Your Practice Protected? A Self-Assessment Checklist
Answer yes or no to each question below, using your last full month of billing activity as the reference point. Count your yes answers, then compare the total with the three-tier scoring guide that follows the list, and assign an owner to each gap you find.
- Do you separate UHC commercial, Medicare Advantage and Community Plan claims at registration?
- Has someone read the filing language in your UnitedHealthcare agreement in the last 12 months?
- Is your working deadline the shorter of the contract number and any statutory number?
- Do most claims reach UnitedHealthcare within five business days of service?
- Do you store clearinghouse acceptance reports with each claim record?
- Do you have an alert near 60 percent of the filing window for unpaid claims?
- Do you check status around day 30 on electronic claims?
- Do you track the primary determination date for every secondary claim?
- Do you review average days to submit by plan line, not only overall?
- Do you review remittances for underpayments within a few months of payment?
Scoring guide: 9 to 10 yes answers suggests a strong process; keep reviewing quarterly. 6 to 8 yes answers suggests gaps; fix each “no” within 30 to 60 days. 0 to 5 yes answers suggests high exposure; audit your filing workflow before the next billing cycle.
When Should a Florida Practice Consider Professional Billing Support?
In-house teams reach a limit when deadline tracking depends on memory instead of a system, or when volume outgrows the people available to work the aging report. Five signals suggest outside help may be worth a look before the next quarter closes:
- CO-29 write-offs appear in more than one month’s remittance reports.
- Staff cannot say which UnitedHealthcare product carries which deadline.
- Secondary or Community Plan claims regularly age past day 60.
- Acceptance reports are not stored with claims.
- One employee holds the deadline knowledge, and turnover would erase it.
When evaluating outside support, look for plan-line deadline tracking, stored proof of submission, reporting on submission lag and write-offs by reason, clear contract and fee terms, and a team that works in a HIPAA-compliant way. EON MED SOLUTIONS is one example: it provides end-to-end medical billing, coding, credentialing, denial management and compliance support through a US-based team with transparent reporting and no hidden fees. Results vary by practice. You can explore the EON MED SOLUTIONS billing and RCM services to see how that support is structured.
Expert Opinion
The UHC Florida timely filing limit is a plan-line question first and a calendar question second. Commercial, Medicare Advantage and Community Plan claims each carry their own clock, and a Florida statute adds a second layer for fully insured plans. A calendar built on one remembered number will be wrong for part of any mixed payer book.
Firm published standards in this guide are the 6-month statutory deadline, the 90-day secondary claim window and the 12-month underpayment limit in Florida statutes. UnitedHealthcare’s 90-day and 365-day figures come from payer guidance and contracts. The five-business-day target and the day 55 alert are practical or illustrative targets.
The natural next question is which of your open UnitedHealthcare claims sit closest to their deadline today, and who owns each one. If you want a second set of eyes on that answer, review how EON MED SOLUTIONS supports billing and revenue cycle workflows.
Frequently Asked Questions
What is the UHC Florida timely filing limit?
It depends on the plan. UnitedHealthcare commercial contracts commonly set at least 90 days from the date of service for participating providers, while Florida statute says providers should file with fully insured primary plans within 6 months. Medicare Advantage and Community Plan claims follow their own contracts and manuals.
What is a good days-to-submit target for UHC claims in Florida?
A commonly used practical target is submission within five business days of service. Many teams also investigate when an average uses more than about half of a plan’s filing window. For a 90-day plan, that is roughly 45 days. These are practical targets, not payer mandates.
What is a good alert point for unpaid UHC claims?
A practical alert point is about 60 percent of the window, which is day 54 on a 90-day plan. At that point, confirm the acceptance report, check claim status and resubmit if needed while enough time remains to prove timely filing.
Does Florida’s 6-month rule apply to self-funded UHC plans?
Generally no. State insurance statutes usually do not govern self-funded employer plans, so the plan document and your agreement set the deadline. Confirm the funding type through the member’s benefit documents or UnitedHealthcare Provider Services before assuming the statutory window helps.
How long do I have to file a secondary claim to UHC in Florida?
For fully insured plans, Florida statute requires the secondary claim within 90 days after the primary payer’s final determination. Contracts may differ, and other plan types follow their own documents. Record the primary determination date on every secondary claim, because that date starts the clock.
What should a practice do after a UHC timely filing denial?
Gather the clearinghouse acceptance report showing receipt inside the window, then appeal within the deadline stated in the denial notice. Without proof of on-time submission, the denied amount is usually written off under the contract, so confirm terms before billing the patient.
Sources and Methodology
(a) Published standards and definitions from named bodies
- Florida Statutes §627.6131 (payment of claims, health insurers) and §641.3155 (prompt payment of claims, health maintenance organizations), including the 6-month submission deadline, the 90-day secondary claim deadline and the underpayment limit added by chapter 2025-45.
- 42 CFR §424.44 (Original Medicare 12-month filing limit).
(b) Named benchmarking data providers
- No benchmarking data provider figures were used in this article.
(c) Practical or illustrative targets from general industry sources
- The five-business-day submission target, the 60 percent alert point, the 90-day figure commonly cited for UnitedHealthcare commercial contracts and the 30 to 60 and 90 to 180 day planning ranges are commonly reported across industry sources or are illustrative. All worked examples are illustrative.
(d) Survey or study data with a named source
- No survey or study data were used in this article.
Payer guidance reviewed: UnitedHealthcare 2026 Care Provider Administrative Guide announcement (effective January 1, 2026 for newly contracted providers and April 1, 2026 for existing providers); UnitedHealthcare Community Plan Florida care provider manual; UnitedHealthcare provider guidance on proof of timely filing. Filing-window language from the Administrative Guide was reviewed through third-party provider-education summaries.
Methodology: This article is a research-based approximation of current search results and payer rules, not verified rank-tracking data. Research was completed in October 2026. Results vary by practice, contract and plan, and figures reflect information available at the time of research.


