
Aetna New York Timely Filing Limit: The 120-Day Rule, the 25% Penalty and the 365-Day Cutoff
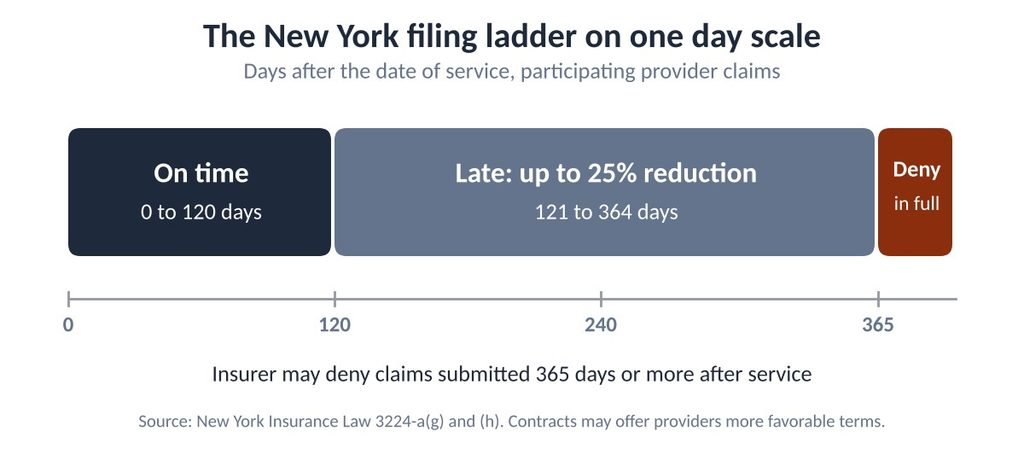
The Aetna New York timely filing limit is 120 days from the date of service for most fully insured claims, set by New York Insurance Law section 3224-a. A participating provider’s late claim can be paid with a reduction of up to 25%. A claim submitted 365 days or more after service may be denied in full.
New York is different from most states because the law, not only the contract, shapes the deadline. A claim filed on day 130 is late but not dead, and a claim filed on day 365 can be refused outright. This guide explains the Aetna New York timely filing limit as a ladder, shows what each rung costs and covers Medicaid and dispute windows. It also gives four calculations and a self-assessment checklist near the end.
The ladder at a glance
| Days after service | Status of a participating provider’s claim | What can happen |
| 0 to 120 | On time | Normal processing; payment due within 30 days (electronic) or 45 days (other) |
| 121 to 364 | Late | Payment may be reduced by up to 25%, or denied and reconsidered |
| 365 or more | Past the cutoff | Insurer may deny in full |
Source: New York Insurance Law section 3224-a(a), (g) and (h). The ladder applies to claims within the statute’s scope; contracts may offer providers more favorable terms.
Key numbers for Aetna in New York
| Metric | Practical target/range | Review frequency | Source type |
| Initial claim submission | 120 days from the date of service | Annually | A |
| Payment reduction for a late claim | Up to 25% of the amount that would have been paid | Per claim | A |
| Full denial cutoff | 365 days or more after the date of service | Per claim | A |
| Insurer payment deadline | 30 days (electronic) or 45 days (other) from receipt | Per claim | A |
| Interest on late insurer payment | Greater of the state corporate rate or 12% per year | Per claim | A |
| Aetna Better Health of New York initial claims | 120 days from service, unless a contract says otherwise | Each plan update | A |
| Aetna reconsideration window | 180 calendar days from the initial claim decision | Each Aetna update | A |
| New York Medicaid fee-for-service | 90 days from service; 2-year final limit | Each Medicaid update | A |
| Claim submission turnaround | Within 30 days of service for 95% or more of claims | Weekly | C |
Source types: A = published government or payer source (New York Insurance Law, New York Medicaid, Aetna web pages). B = named benchmarking data provider (none used). C = practical planning target from common industry practice. D = survey or study data (none used). Confirm against your contract and current documents.
What New York Insurance Law section 3224-a actually requires
New York Insurance Law section 3224-a, titled “Standards for prompt, fair and equitable settlement of claims for health care and payments for health care services,” requires providers to submit claims within 120 days. Subsection (g)(1) says health care claims must be initially submitted within 120 days after the date of service, and it lets the parties agree to terms more favorable to the provider. You can read the full text on the New York Senate website.
Subsection (h) is the part most billers miss. A participating provider may request reconsideration of a claim denied only for late submission, and the insurer must pay if the provider shows an “unusual occurrence” and a pattern or practice of timely submissions. The insurer may otherwise reduce payment by up to 25%, and it may deny claims submitted 365 days or more after service.
Does the law apply to stale claims?
Yes. A 2001 informal opinion from the New York State Insurance Department’s General Counsel concluded that section 3224-a applies to “stale claims,” meaning claims denied for being submitted too long after service. Insurers must still meet the payment and notice deadlines when they deny for lateness. The opinion is more than twenty years old, so treat it as background, not a current ruling.
The statute also sets the insurer’s side of the clock. Electronic claims are due for payment within 30 days of receipt and other claims within 45 days. A denial or partial approval needs written notice within 30 calendar days. Late payments carry interest at the greater of the state corporate rate or 12% per year.
In billing audits, a common pattern is that offices treat the 120 days as a hard wall and write off claims on day 121. Under subsection (h), a participating provider’s late claim may still be payable, so check the reconsideration route before you adjust the balance.
What Aetna Better Health of New York and Aetna’s dispute rules say
Aetna Better Health of New York, Aetna’s Medicaid managed care program in the state, states that claims must be filed within 120 days of the date services were provided, unless there is a contractual exception. Its provider claims page also says disputes must be submitted in writing within 60 calendar days of the reconsideration response, counted from the explanation of payment date. See the Aetna Better Health of New York claims page.
Aetna’s broader dispute process uses different clocks. Its disputes overview says to file a reconsideration within 180 calendar days of the initial claim decision and an appeal within 60 calendar days of the reconsideration decision. Its provider appeals page lists state exceptions, but New York does not appear in either table, so the 180-day standard appears to govern. Confirm that with Aetna before relying on it.
| Aetna route | Window | Source |
| Initial claim, Aetna Better Health of New York | 120 days from service | Aetna Better Health of New York claims page |
| Written dispute, Aetna Better Health of New York | 60 calendar days from the reconsideration response | Same page |
| Reconsideration, Aetna commercial and Medicare | 180 calendar days from the initial decision | Aetna disputes overview |
| Appeal after reconsideration | 60 calendar days from the reconsideration decision | Aetna disputes overview |
| Commercial and Medicare Advantage initial claim | Statute sets 120 days for covered plans; Medicare Advantage and self-funded plans follow contract and federal rules | Participation agreement |
Source: pages cited above. A dispute window is not a filing window.
Timely filing versus appeal filing limits
A dispute window never reopens a missed filing deadline, and our guide to timely filing versus appeal filing limits explains why. Competitor guides often give 90 days for in-network commercial claims with no Aetna source. New York’s 120-day statutory default is longer, and the law lets contracts offer providers more favorable terms, not less. A contract that says 90 days raises a legal question, so ask counsel and Aetna before you rely on either number.
New York Medicaid runs on a shorter clock
New York Medical Assistance claims must be initially submitted within 90 days of the date services were furnished, according to the state’s Guide to Timely Billing, dated August 9, 2018. Claims with errors must be corrected and resubmitted within 60 days of notification, and claims must be finally submitted within 2 years. The eMedNY Guide to Timely Billing lists delay reason codes with their own deadlines, mostly 30 days from the triggering event.
Managed care is different again. Subsection (g)(1) lets Medicaid managed care contracts set another period, but never less than 90 days. Check the plan’s manual and your contract for each Medicaid plan, and compare our guides to corrected claim deadlines by payer and secondary claim timely filing deadlines.
Four calculations to run before a claim slips down the ladder
Four short calculations turn the statute into dates and dollars. Run the first two on any claim older than 60 days, and the last two monthly. Each shows the formula first, then an illustrative scenario with real numbers that your team can copy into a spreadsheet.
Calculation 1: the 120-day deadline
Formula: deadline = date of service + 120 days.
Illustrative scenario (not an actual client record): a visit occurs on August 10, 2026, so the 120-day deadline is December 8, 2026. On October 16, 2026, 67 days have passed and 53 remain. A claim still unbilled at day 67 belongs on a daily worklist.
Calculation 2: the 365-day cutoff
Formula: cutoff = date of service + 365 days, after which the insurer may deny in full.
Illustrative scenario (not an actual client record): a service occurred on October 20, 2025, so the cutoff is October 20, 2026. On October 16, 2026, 361 days have passed and 4 remain. A claim filed after the cutoff can be denied in full, so this one needs to go out today.
Calculation 3: the cost of a late claim
Formula: lowest payment = allowed amount × (1 − 0.25).
Illustrative scenario (not an actual client record): a participating provider’s claim has an allowed amount of $200 and is filed on day 150. The insurer may reduce payment by up to $50, so payment could be as low as $150. Across 40 such claims a month, a $50 maximum reduction would remove up to $2,000.
Calculation 4: interest on a late insurer payment
Formula: interest = claim amount × annual rate × days late ÷ 365.
Illustrative scenario (not an actual client record): a $1,000 electronic claim is paid 20 days after the 30-day deadline. At the 12% statutory floor, interest is $1,000 × 0.12 × 20 ÷ 365, or $6.58. The statute sets the rate at the greater of the state corporate rate or 12%, so your interest could be higher. Track it, because small amounts add up across a month of claims.
Reading the on-time rate without being fooled by the average
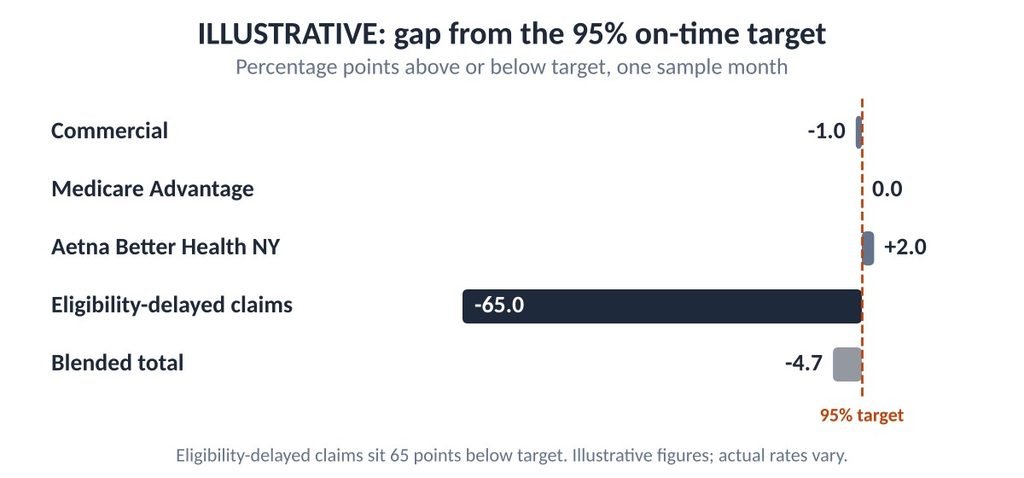
Compare like for like. Commercial, Medicare Advantage and Medicaid claims run on different clocks, so each belongs in its own row of your report. A blended rate can look healthy while one group sits far below target.
Illustrative scenario (not an actual client record): one month of Aetna claims, split by product and by trigger, with the blended total that most dashboards report shown beside it.
| Claim group (Illustrative) | Claims | Submitted within 30 days | On-time rate |
| Commercial (fully insured) | 150 | 141 | 94.0% |
| Medicare Advantage | 120 | 114 | 95.0% |
| Aetna Better Health of New York | 100 | 97 | 97.0% |
| Claims delayed by eligibility checks | 30 | 9 | 30.0% |
| Blended total | 400 | 361 | 90.3% |
Illustrative figures; actual rates vary by practice, specialty and plan mix.
The blended 90.3% looks close to a 95% practical target, but the eligibility-delayed group sits at 30%. A single average would hide it. One missed benchmark is a signal to investigate, not a verdict, so check whether registration or a stalled eligibility batch caused the delay.
A late-claim decision path for Aetna New York
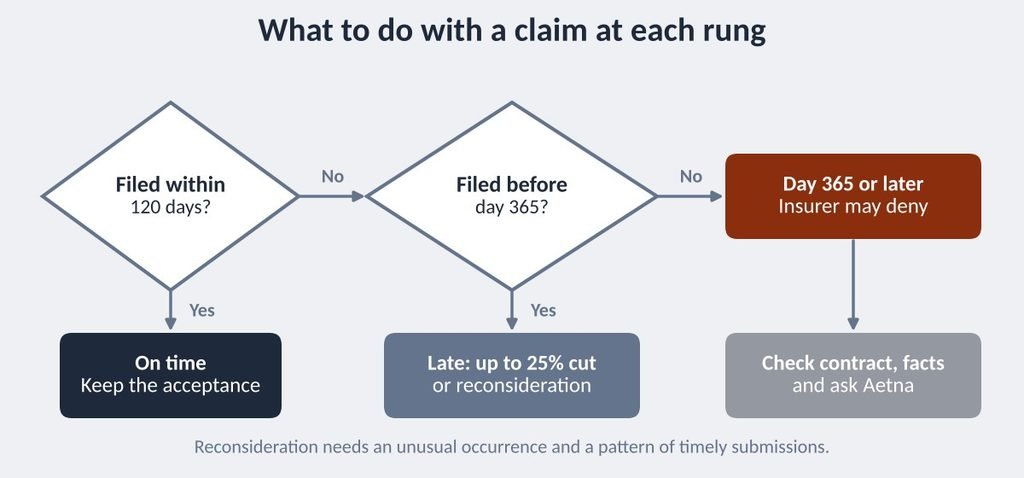
A claim past 120 days needs a decision, not a write-off. The path below applies when a participating provider’s claim has already crossed a rung of the ladder, and each step names the evidence to keep:
- Confirm the date of service and the date Aetna received the claim, from the acknowledgment, not the billing date.
- If the claim is under 120 days, file today and keep the acceptance report.
- If it is between 121 and 364 days, file and expect a possible reduction of up to 25%, or request reconsideration if it is denied only for lateness.
- If it is 365 days or more, check the contract and the facts, because the insurer may deny in full.
- For a reconsideration, document the unusual occurrence and your record of timely submissions, and send both with the request.
In billing audits, a common pattern is that reconsideration requests fail because they describe the delay but not the practice’s history. Subsection (h) asks for both an unusual occurrence and a pattern of timely submissions, so pull a clean-claim history report before you write the request. A team facing a backlog may want help with denial management.
Habits that keep Aetna New York claims inside 120 days
A workable routine has six steps, each tied to a trigger such as a new patient, a primary payer remittance or a denial, and the list below shows the order most offices can adopt:
- Record the product and funding type at registration, and write the window in a deadline table; our guide to payer-specific claim submission rules shows the layout.
- Submit within 30 days of service as a practical target, and save the acknowledgment; the guide to clean claim rate improvement covers common rejection causes.
- Flag unpaid claims at 30, 60 and 90 days because the New York window is short; our method for tracking unpaid claims across payers works here.
- Date-stamp every primary payer remittance on the day it arrives.
- Review denials monthly by product, and check each late denial for a reconsideration route.
- Refer aging balances to A/R management support when the in-house team cannot clear them.
Our walkthrough on how to track timely filing deadlines shows a spreadsheet layout. If the patient also has Medicare, the Medicare 12-month rule guide covers that coverage. For contrast with other states, read our guides to Aetna Texas and Aetna California.
How long until the routine shows results?
These are general planning ranges, not guarantees. A deadline table and a daily worklist often reduce last-minute submissions within two to four weeks. Late-payment and denial trends take longer to read. Three to six months of data is a reasonable horizon, and a full year shows whether reconsiderations are filed on time.
Mistakes that push claims down the ladder
- Treating day 120 as a hard stop. Late claims may still be payable with a reduction.
- Ignoring the 365-day cutoff. A claim at or past day 365 may be denied in full.
- Using the Medicaid 90-day rule for commercial claims. Apply the clock that matches the plan.
- Citing 90 days for commercial claims without an Aetna source. Check the contract.
- Sending a reconsideration without proof. Document the unusual occurrence and the timely-submission pattern.
- Confusing dispute and filing windows. Disputes run on separate clocks.
Quick summary
- The Aetna New York timely filing limit is 120 days from the date of service for most fully insured claims.
- A participating provider’s late claim may be paid with a reduction of up to 25%.
- Claims at or past 365 days may be denied in full.
- Aetna Better Health of New York states 120 days and a 60-day written dispute window.
- New York Medicaid fee-for-service runs 90 days, with a 2-year final limit.
- A practical target is submission within 30 days of service for 95% or more of claims.
Self-assessment: is your Aetna New York process safe?
Answer yes or no to each question below, then count your yes answers and compare the total with the three-tier scoring guide that follows the list of ten questions:
- Do you build deadlines from the date of service?
- Do you know whether each Aetna patient is fully insured, self-funded or Medicare Advantage?
- Do 95% or more of claims go out within 30 days of service?
- Do you flag unpaid claims at 30, 60 and 90 days?
- Do you know how many claims you filed after day 120 last quarter?
- Do you request reconsideration before writing off a lateness denial?
- Do you keep clean-claim history reports for reconsideration requests?
- Do you keep clearinghouse acceptances and Aetna acknowledgments?
- Do you track on-time rates separately by product?
- Do you review late-filing denials monthly?
Scoring guide: 9 to 10 yes answers suggests a well-controlled process, so review it quarterly. 6 to 8 yes answers suggests gaps; fix the “no” items first, starting with questions 2 and 5. 0 to 5 yes answers suggests high exposure to payment reductions and a good moment for an outside review.
When outside billing help makes sense
Outside support is worth considering when the in-house approach has reached its limits. These five signals suggest that point has arrived for a New York practice billing several Aetna products, whether commercial, Medicare Advantage or Medicaid:
- Claims regularly go out after day 120.
- Nobody can say how much was lost to late-filing reductions last quarter.
- Lateness denials are written off without a reconsideration request.
- Staff cannot tell fully insured Aetna plans from self-funded ones.
- Deadline tracking depends on one person’s spreadsheet.
Look for a billing partner that keeps a written deadline table by payer and product and retains acknowledgments. It should also report on-time rates by product and work reconsiderations with documentation. Transparent reporting and clear pricing matter as much as the deadlines.
EON MED SOLUTIONS is one example: a US-based team that delivers medical billing, coding, credentialing, denial management and A/R follow-up with transparent reporting and no hidden fees. Results vary by practice. You can review the EON MED SOLUTIONS billing, coding and RCM services to see how the work is organized.
Expert Opinion
The Aetna New York timely filing limit is a ladder, not a single wall. The firm published standards in this guide are the 120-day, 25% and 365-day provisions of Insurance Law section 3224-a, the insurer payment and interest rules, the New York Medicaid 90-day rule, and the windows stated on Aetna’s pages. The 30-day submission goal and the 30, 60 and 90 day alerts are practical targets.
The worked examples are illustrative scenarios, not client results. They show how to turn a rule into a date and a dollar figure, and how a blended rate can hide a 30% subgroup. Because the statute, Medicaid rules and Aetna’s pages change, recheck the numbers each year.
The natural next question is how many of last quarter’s claims went out after day 120. If you cannot answer it, a team that tracks submission dates daily can help; start with EON MED SOLUTIONS’ billing and RCM services.
Frequently asked questions
What is the Aetna New York timely filing limit?
For most fully insured claims, New York Insurance Law section 3224-a sets 120 days from the date of service. A participating provider’s late claim may be paid with a reduction of up to 25%, and claims at or past 365 days may be denied in full. Medicare Advantage and self-funded plans follow contracts and federal rules.
Can Aetna deny a New York claim for filing after 120 days?
Not automatically. A participating provider may request reconsideration of a claim denied only for lateness, and the insurer must pay if the provider shows an unusual occurrence and a pattern of timely submissions. Otherwise the insurer may reduce payment by up to 25%, and it may deny claims at 365 days or more.
What is a good claim submission turnaround for New York claims?
A practical target is submitting most claims within a few business days, with 95% or more out within 30 days of service. This is an industry planning target, not a legal requirement. Early filing keeps most of the 120-day window in reserve for rejections and corrections.
What is a good on-time submission rate for Aetna claims?
No published benchmark exists. A practical goal is 95% or more within 30 days of service, tracked separately for commercial, Medicare Advantage and Medicaid claims. When one group falls well below the blended rate, investigate that group’s trigger event first.
What is a good aging alert schedule for New York claims?
Because the statutory window is 120 days, many practices flag unpaid claims at 30, 60 and 90 days from service. This is a planning schedule, not a legal rule. The 90-day flag leaves about a month to file or request reconsideration before day 120.
How long does Aetna Better Health of New York allow for disputes?
Aetna Better Health of New York states that disputes must be submitted in writing within 60 calendar days of the reconsideration response, counted from the explanation of payment date. Its initial claim window is 120 days from service. Confirm the current page and any contract exception before you file.
Sources and methodology
(a) Published standards and definitions from named bodies
- New York Insurance Law section 3224-a, Standards for prompt, fair and equitable settlement of claims: New York State Senate.
- New York State Insurance Department, Office of General Counsel, informal opinion of September 20, 2001, on the application of section 3224-a to stale claims: DFS.
- Aetna Better Health of New York, provider claims page: Aetna Better Health.
- Aetna provider appeals page with state exceptions (page metadata modified August 14, 2026): Aetna, and Aetna’s disputes and appeals overview page.
- New York State Department of Health, Guide to Timely Billing, August 9, 2018, citing 18 NYCRR 540.6(a)(1): eMedNY.
(b) Named benchmarking data providers. None used in this article.
(c) Practical or illustrative targets from general industry sources
- National Aetna timely filing guides (Muni Health, MedSole RCM, Billing Care Solutions) were reviewed for how competitors present Aetna rules. They cite 90 days for in-network commercial claims without an Aetna document, mention New York only in passing and do not cite Insurance Law section 3224-a.
- The 30-day submission goal, the 95% target and the 30, 60 and 90 day alerts are practical planning targets. All worked-example figures are illustrative.
(d) Survey or study data. None used in this article.
Methodology: the research reviewed the top results for the keyword, the text of Insurance Law section 3224-a, Aetna and Aetna Better Health of New York pages, and New York Medicaid billing guidance in October 2026. Aetna’s commercial and Medicare Advantage provider manuals were not available for review, so the article does not state a commercial or Medicare Advantage day count as fact. The statute’s scope for self-funded and Medicare Advantage plans is not addressed in the text reviewed. Results vary by contract, product and funding type, and figures reflect information available at the time of research. Confirm every deadline against your current contract and the cited sources.


