
BCBS New York Timely Filing Limit: Which Blue Plan Sets Your Deadline in 2026?
The BCBS New York timely filing limit is the deadline for a Blue plan to receive a claim, and no single number applies. Empire BlueCross BlueShield and Excellus BlueCross BlueShield publish 120 days for professional commercial claims, Highmark Blue Cross Blue Shield allows 365 days in western and northeastern New York, and Medicaid managed care plans can use 90 days.
Two practices can bill a patient with a Blue card for the same date of service and face a 120-day deadline in one case and a 365-day deadline in the other. The BCBS New York timely filing limit depends on which Blue licensee issued the card, which product the member holds, and what the provider agreement says.
This guide separates the carriers, adds New York’s statutory floor, explains Highmark’s September 2026 corrected-claim change, and shows how to build deadline alerts. A self-assessment checklist near the end lets you score your own process, and the sources section names every document behind the numbers.
| Situation | Usual window |
| Anthem (Empire) commercial professional claims | 120 days from date of service |
| Excellus professional claims | 120 days; hospitals follow the contract |
| Highmark initial claims, western and northeastern New York | 365 days from service, discharge or last treatment |
| Medicaid managed care under a Blue brand | 90 days at Anthem for participating providers; 120 days in Highmark’s policy |
Carrier policies change and vary by contract. The sections below give sources and exceptions.
BCBS New York filing numbers at a glance
Three Blue licensees set at least five different windows for New York claims. The table below separates published carrier policies from practical billing targets so that each number carries its source type, and it reflects information available in October 2026.
| Metric | Practical target or range | Review frequency | Source type |
| State default filing window, state-regulated plans | 120 days from date of service | At contract renewal | S: NY Insurance Law §3224-a(g) |
| Anthem (Empire) commercial professional claims | 120 days from date of service | Each January | P: Empire provider notice, 2019 |
| Anthem (Empire) Medicare Advantage professional claims | 90 days from date of service | Each January | P: Empire provider notice, 2019 |
| Excellus professional claims | 120 days; hospitals follow the contract | Each January | P: Excellus billing guidebook |
| Highmark initial claims (WNY and NENY) | 365 days from service, discharge or last treatment | Each January | P: Highmark provider manual |
| Highmark corrected claims | 15 months (455 days) from original claim finalization | Quarterly | P: Highmark notice, effective Sept. 1, 2026 |
| Anthem NY Medicaid, participating providers | 90 days; 15 months if non-participating | At contract renewal | P: Anthem NY Medicaid policy |
| Internal submission lag and CO-29 rate | 5 business days or fewer; under 1% of claims | Weekly and monthly | G: commonly used billing targets |
Source labels: S = statute. P = payer publication. G = practical target commonly used across billing teams; not a legal or payer requirement. Carrier documents vary in age, so confirm each figure in your current manual.
What is the BCBS New York timely filing limit, and who sets it?
No single body sets it. Blue Cross Blue Shield is a federation of independent licensees. Each writes its own filing rule into its agreement and manual. New York providers mainly deal with Anthem Blue Cross and Blue Shield, Excellus BlueCross BlueShield, and Highmark in the western and northeastern parts of the state. Anthem took over the Empire BlueCross BlueShield name on January 1, 2024, and Empire-branded cards remain valid.
State law adds a floor. New York Insurance Law §3224-a(g) requires providers to submit claims within 120 days after the date of service for the claim to be valid against covered insurers and HMOs, and it allows terms more favorable to the provider. Subsection (g) governs initial submission; subsection (h), covered below, governs reconsideration of late claims. Highmark’s 365 days fits the rule. When a commercial agreement states fewer than 120 days, ask the carrier how the statute applies.
Scope matters. The statute reaches insurers and HMOs licensed in New York, so self-funded employer plans that a Blue plan only administers generally follow the plan document and your agreement. A New York practice treating a member whose policy was issued in another state follows that policy’s rules.
Reference sites often list “BCBS New York” as one year, which matches Highmark’s policy but not the downstate and upstate carriers. Others apply Anthem’s 90-day multi-state figure to New York commercial plans. That conflicts with Empire’s own notice keeping commercial claims at 120 days. Compare the payer-specific claim submission rules with each carrier’s manual before trusting a chart.
In billing audits, a common pattern is one “BCBS” payer row in the practice management system covering three carriers. A single deadline then gets applied to all of them, and the shortest-window carrier produces the denials. Splitting the row by carrier and line is a small setup task that removes the problem.
Anthem Blue Cross and Blue Shield (Empire): 120 days commercial, 90 days Medicare Advantage
Anthem, then branded Empire, kept commercial claims at 120 days from the date of service in a July 2019 provider notice and moved professional Medicare Advantage claims to 90 days for claims submitted on or after October 1, 2019. A Medicare Advantage claim therefore does not get the longer treatment that Original Medicare’s 12-month rule gives fee-for-service claims.
Anthem’s New York Medicaid policy is separate. Its Claims Timely Filing reimbursement policy sets 90 days for participating providers and 15 months for non-participating providers. Several reference sites attach the 15-month figure to Empire commercial plans, but the published pair sits in the Medicaid policy. Confirm the line of business before applying it. Check the current provider manual too, because the commercial notice is several years old.
Excellus BlueCross BlueShield: a 120-day window for professional claims
Excellus applies a 120-day filing limit to professional providers, sends hospitals to their contracts, and starts coordination-of-benefits claims from the primary payer’s payment date. Its billing orientation guidebook states that claims submitted after the limit are denied for late filing.
Excellus also publishes a Request for Timely Filing Review form for circumstances beyond the provider’s or member’s control. The form and documents must reach Excellus within 120 days of the remittance. Participating providers who miss the contractual limit cannot bill members for covered services, except for non-Excellus BlueCard members.
Highmark BCBS and Blue Shield: 365 days, plus a new corrected-claim rule
Highmark requires initial claims within 365 days of the date of service, discharge date or last date of treatment, counting weekends, under its New York timely filing policy. That is the longest published window among the New York Blue carriers. Highmark Western and Northeastern New York Inc. does business as Highmark Blue Cross Blue Shield in the west and Highmark Blue Shield in the northeast, and the manual’s New York policy names both.
The corrected claim rule changed on September 1, 2026. Highmark’s notice says corrected claims must arrive within 15 months (455 calendar days) of the finalization date of the original claim, and later ones deny for timely filing. The rule covers commercial, Medicare Advantage and Federal Employee Program lines. Count from finalization, not receipt, and see corrected claim deadlines by payer for other carriers.
In billing audits, a common pattern is corrected claims calendared from the original date of service because that is how the initial window works. For Highmark, that habit shortens a 455-day window and triggers needless rushing. The reverse habit at a carrier that counts from service causes misses.
When Highmark is secondary, attach the primary payer’s EOB showing the adjudication date. Secondary claims outside the period deny, and both Highmark and the member are held harmless. The secondary claim timely filing rules explain how the clock moves in crossover billing.
Which clock applies to BlueCard, Medicaid and federal employee claims?
Out-of-area BlueCard claims are billed to the local Blue plan the same way as local members’ claims, so the local plan’s filing limit is the working deadline. Confirm it in the local manual when contract language is unclear. Federal Employee Program claims follow the plan’s FEP guidance, and Highmark’s corrected-claim rule names that line explicitly.
Blue-branded Medicaid plans follow their own policies. Anthem’s New York Medicaid plan uses 90 days for participating providers, while Highmark’s Medicaid managed care policy lists 120 days. Both give non-participating providers 15 months. Statute lets Medicaid contracts use a different period, but never under 90 days, so a 90-day alert is the safe default until you read the contract.
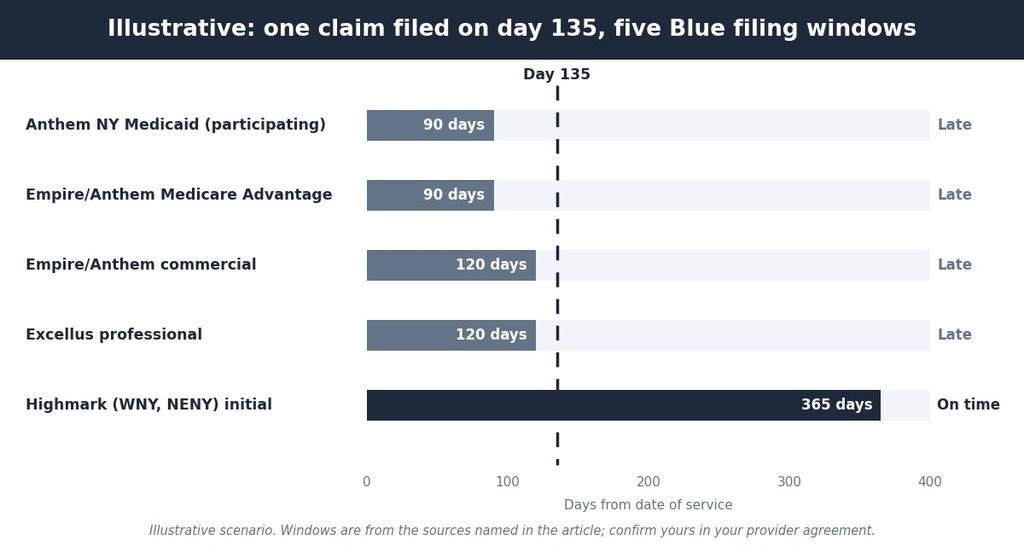
The chart below shows why the carrier matters. The same claim, filed on day 135, is late at four of the five windows and on time at one, so a single shared alert would misjudge most of them. Read each bar against the carrier’s own manual, not against a general chart.
What is the BCBS New York timely filing limit, and who sets it?
No single body sets it. Blue Cross Blue Shield is a federation of independent licensees. Each writes its own filing rule into its agreement and manual. New York providers mainly deal with Anthem Blue Cross and Blue Shield, Excellus BlueCross BlueShield, and Highmark in the western and northeastern parts of the state. Anthem took over the Empire BlueCross BlueShield name on January 1, 2024, and Empire-branded cards remain valid.
State law adds a floor. New York Insurance Law §3224-a(g) requires providers to submit claims within 120 days after the date of service for the claim to be valid against covered insurers and HMOs, and it allows terms more favorable to the provider. Subsection (g) governs initial submission; subsection (h), covered below, governs reconsideration of late claims. Highmark’s 365 days fits the rule. When a commercial agreement states fewer than 120 days, ask the carrier how the statute applies.
Scope matters. The statute reaches insurers and HMOs licensed in New York, so self-funded employer plans that a Blue plan only administers generally follow the plan document and your agreement. A New York practice treating a member whose policy was issued in another state follows that policy’s rules.
Reference sites often list “BCBS New York” as one year, which matches Highmark’s policy but not the downstate and upstate carriers. Others apply Anthem’s 90-day multi-state figure to New York commercial plans. That conflicts with Empire’s own notice keeping commercial claims at 120 days. Compare the payer-specific claim submission rules with each carrier’s manual before trusting a chart.
In billing audits, a common pattern is one “BCBS” payer row in the practice management system covering three carriers. A single deadline then gets applied to all of them, and the shortest-window carrier produces the denials. Splitting the row by carrier and line is a small setup task that removes the problem.
Anthem Blue Cross and Blue Shield (Empire): 120 days commercial, 90 days Medicare Advantage
Anthem, then branded Empire, kept commercial claims at 120 days from the date of service in a July 2019 provider notice and moved professional Medicare Advantage claims to 90 days for claims submitted on or after October 1, 2019. A Medicare Advantage claim therefore does not get the longer treatment that Original Medicare’s 12-month rule gives fee-for-service claims.
Anthem’s New York Medicaid policy is separate. Its Claims Timely Filing reimbursement policy sets 90 days for participating providers and 15 months for non-participating providers. Several reference sites attach the 15-month figure to Empire commercial plans, but the published pair sits in the Medicaid policy. Confirm the line of business before applying it. Check the current provider manual too, because the commercial notice is several years old.
Excellus BlueCross BlueShield: a 120-day window for professional claims
Excellus applies a 120-day filing limit to professional providers, sends hospitals to their contracts, and starts coordination-of-benefits claims from the primary payer’s payment date. Its billing orientation guidebook states that claims submitted after the limit are denied for late filing.
Excellus also publishes a Request for Timely Filing Review form for circumstances beyond the provider’s or member’s control. The form and documents must reach Excellus within 120 days of the remittance. Participating providers who miss the contractual limit cannot bill members for covered services, except for non-Excellus BlueCard members.
Highmark BCBS and Blue Shield: 365 days, plus a new corrected-claim rule
Highmark requires initial claims within 365 days of the date of service, discharge date or last date of treatment, counting weekends, under its New York timely filing policy. That is the longest published window among the New York Blue carriers. Highmark Western and Northeastern New York Inc. does business as Highmark Blue Cross Blue Shield in the west and Highmark Blue Shield in the northeast, and the manual’s New York policy names both.
The corrected claim rule changed on September 1, 2026. Highmark’s notice says corrected claims must arrive within 15 months (455 calendar days) of the finalization date of the original claim, and later ones deny for timely filing. The rule covers commercial, Medicare Advantage and Federal Employee Program lines. Count from finalization, not receipt, and see corrected claim deadlines by payer for other carriers.
In billing audits, a common pattern is corrected claims calendared from the original date of service because that is how the initial window works. For Highmark, that habit shortens a 455-day window and triggers needless rushing. The reverse habit at a carrier that counts from service causes misses.
When Highmark is secondary, attach the primary payer’s EOB showing the adjudication date. Secondary claims outside the period deny, and both Highmark and the member are held harmless. The secondary claim timely filing rules explain how the clock moves in crossover billing.
Which clock applies to BlueCard, Medicaid and federal employee claims?
Out-of-area BlueCard claims are billed to the local Blue plan the same way as local members’ claims, so the local plan’s filing limit is the working deadline. Confirm it in the local manual when contract language is unclear. Federal Employee Program claims follow the plan’s FEP guidance, and Highmark’s corrected-claim rule names that line explicitly.
Blue-branded Medicaid plans follow their own policies. Anthem’s New York Medicaid plan uses 90 days for participating providers, while Highmark’s Medicaid managed care policy lists 120 days. Both give non-participating providers 15 months. Statute lets Medicaid contracts use a different period, but never under 90 days, so a 90-day alert is the safe default until you read the contract.
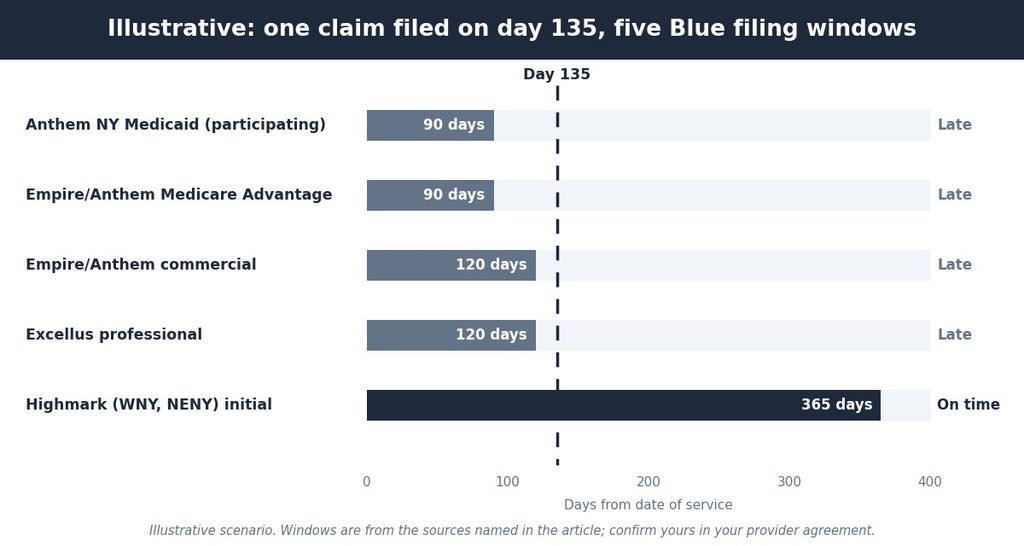
The chart below shows why the carrier matters. The same claim, filed on day 135, is late at four of the five windows and on time at one, so a single shared alert would misjudge most of them. Read each bar against the carrier’s own manual, not against a general chart.
What happens when a Blue claim misses the New York deadline?
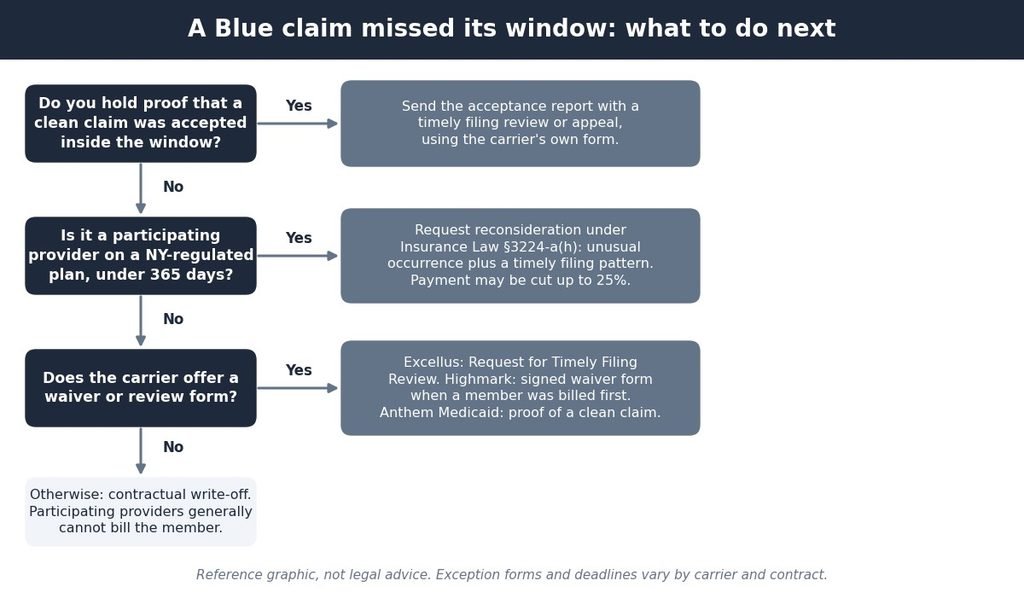
A claim filed after its window is denied as a timely filing denial, usually with CARC 29 under the CO-29 group code, and participating providers generally cannot bill the member. New York law gives participating providers a narrow second chance under §3224-a(h): the insurer must permit reconsideration when a claim was denied only for lateness.
The insurer must pay if the provider shows an unusual occurrence caused the delay and a pattern of timely filing. It may reduce payment by up to 25%, and after 365 days from the date of service it may deny the claim in full. Request reconsideration with documentation when the claim is under 365 days old and your history is clean.
Carrier tools sit alongside the statute. Excellus offers its timely filing review form. Highmark accepts an appeal with proof of timely filing, and when a member was billed first and Blue coverage surfaced later, the signed waiver or patient responsibility form goes with the appeal. Anthem’s Medicaid policy asks for documentation that a clean claim was filed inside the limit. Calendar the filing and appeal clocks separately, as timely filing versus appeal limits explains.
Illustrative scenario (not an actual client record): an Empire commercial claim with a $200 allowed amount reaches the carrier on day 135. If reconsideration succeeds, the largest cut is $50, so payment is at least $150. The same claim sent to Highmark on day 135 is on time and pays in full. When late requests outgrow staff capacity, denial management services can handle documentation and follow-up.
How do you calculate each Blue deadline?
Four calculations turn the carrier rules into dates and rates. Each has a formula and one numeric walkthrough, and each should be rerun with your own window whenever a manual or contract changes. Keep the carrier manual open while you work through them, because small wording differences change the clock start.
Deadline date
Deadline = last date of service + filing window in days
For a service on March 3, 2026, a 120-day window ends July 1, 2026, a 90-day window ends June 1, 2026, and Highmark’s 365-day window ends March 3, 2027. Use the carrier and line of business, not the card name, to choose the window.
Highmark corrected-claim deadline
Corrected-claim deadline = original claim finalization date + 455 days
If Highmark finalized the original claim on July 14, 2026, the corrected claim must arrive by October 12, 2027. Pull the finalization date from the remittance rather than from your submission log. Send the correction well before that date when the claim touches a payment you rely on.
Alert dates
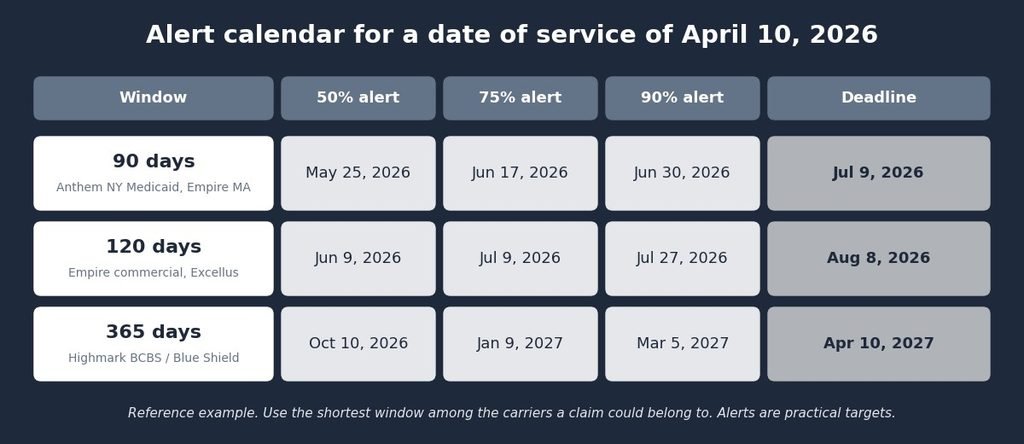
Alert day = date of service + (window × 50%, 75% and 90%)
For a 120-day window and a service on April 10, 2026, alerts fall on June 9, July 9 and July 27, with a deadline of August 8. These thresholds are practical targets, not carrier rules. Set shared alerts from the shortest window when a claim could belong to more than one carrier.
CO-29 denial rate
CO-29 rate = (CO-29 denials ÷ claims submitted) × 100
Illustrative scenario (not an actual client record): a practice submits 1,200 Blue claims and receives 19 CO-29 denials, a blended rate of 1.6%. The table breaks the same claims out by carrier and line, which shows how the average hides two problem areas.
Illustrative
| Carrier and line (illustrative) | Claims submitted | CO-29 denials | CO-29 rate |
| Anthem (Empire) commercial | 450 | 4 | 0.9% |
| Anthem (Empire) Medicare Advantage | 150 | 6 | 4.0% |
| Excellus professional | 300 | 3 | 1.0% |
| Highmark initial claims | 200 | 1 | 0.5% |
| Anthem NY Medicaid | 100 | 5 | 5.0% |
| Blended total | 1,200 | 19 | 1.6% |
Illustrative figures only. Actual denial rates vary by practice, payer mix and specialty.
The blended 1.6% looks acceptable, but two lines run at 4.0% and 5.0%, which is roughly two and a half to three times the blended rate. Investigate each line that exceeds the 1% target, and use reporting and analytics by carrier so one average cannot hide a short-window line.
How should you use these numbers correctly?
Compare like with like. Measure each carrier and line of business on its own, because a blended rate mixes 90-day, 120-day and 365-day windows. A 4% rate on a 90-day line is a different problem from a 4% rate on a 365-day line, so pair the rate with the window.
Treat one missed benchmark as a signal to investigate, not a verdict. When a single month spikes on one carrier, pull the claims, check which window applied and look for a rejection backlog before changing the whole process. The billing KPIs to track page lists companion measures.
How long does it take to fix a Blue filing problem?
Alerts and daily rejection work often show up in CO-29 trends within 30 to 60 days. Clearing aged claims and settling contract questions commonly takes 90 to 180 days. These are general planning ranges, not guarantees, and they depend on claim volume and staffing.
Start with claims nearest their limits, and sort the open list by days remaining so the oldest stay in front of the team. When one carrier’s window is much shorter than its peers, raise it at renewal using these payer contract negotiation tips, because §3224-a(g) supports longer terms for providers.
What is the step-by-step process for tracking Blue deadlines?
A five-step routine ties every Blue claim to a verified window. The steps below build on how to track timely filing deadlines across payers and on tracking unpaid claims after submission. Assign one owner per step when the team is small, so nothing depends on memory.
- Identify the carrier and line. Read the card prefix and eligibility response to separate Anthem, Excellus, Highmark, Medicaid and Medicare Advantage. Call the carrier when a BlueCard prefix is unfamiliar.
- Write the window with its source. Record the number, the clock start and the manual page. Use the shorter window until the contract is read when two sources disagree.
- Set alerts at 50%, 75% and 90%. Add a manager review at 75% when a claim is unpaid or rejected.
- Submit and keep acceptance proof. Send electronically, store the clearinghouse acceptance report, and rework rejections within two business days.
- Track corrected and secondary claims on their own clocks. Count Highmark corrections from finalization and secondary claims from the primary payer’s payment or EOB.
Which mistakes cost the most with BCBS New York claims?
| Mistake | Why it happens | Fix |
| Applying 90 days to every Blue claim | Multi-state Anthem articles are applied to New York | Map each carrier and line to its own source; rebuild the chart at each renewal |
| Using 365 days for all Blue plans | “BCBS New York is one year” appears on many sites | Confirm that 365 days belongs to Highmark before extending it to Empire or Excellus |
| Counting corrected claims from service | Habit from the initial-claim clock | Count Highmark corrections from original finalization when a claim is adjusted |
| Treating submission as acceptance | Rejections sit unworked | Work rejections within two business days and file the acceptance report |
| Giving Medicaid the commercial alert | One payer row covers all lines | Set a 90-day alert on Medicaid managed care claims until the contract says otherwise |
Fixes apply when the condition in the third column matches your workflow.
Quick summary
- The BCBS New York timely filing limit depends on the carrier, the line of business and your provider agreement.
- Published windows include 120 days at Empire and Excellus for professional commercial claims and 365 days at Highmark.
- Anthem (Empire) Medicare Advantage professional claims use 90 days, and Anthem Medicaid uses 90 days for participating providers.
- Highmark corrected claims have a 15-month window from original finalization, effective September 1, 2026.
- New York law sets a 120-day default and allows reconsideration with up to a 25% reduction when the delay was an unusual occurrence.
- A practical target is submission within 5 business days and a CO-29 rate under 1%, tracked by carrier.
Self-assessment: is your Blue claim deadline process under control?
Answer yes or no to each question, and count a partial answer as no. Add up your yes answers and use the scoring guide that follows the list. Repeat the exercise each quarter, because carriers update manuals and your payer mix changes.
- Does your payer list separate Anthem (including Empire-branded cards), Excellus and Highmark?
- Is each carrier’s window stored with its source document and a review date?
- Can intake staff tell Medicare Advantage and Medicaid claims from commercial ones?
- Do most claims leave your office within 5 business days of the visit?
- Is your CO-29 rate under 1%, measured by carrier and line?
- Do alerts use the shortest window that could apply to the claim?
- Do you keep a clearinghouse acceptance report for every claim?
- Are rejected claims reworked within 2 business days?
- Do you count Highmark corrected claims from original finalization?
- Do you know how your local plan times BlueCard and secondary claims?
| Yes answers | What it suggests |
| 8 to 10 | Carrier-ready. Review windows each January and at every contract renewal. |
| 5 to 7 | Partly mapped. Fix carrier mapping, proof and alerts first. |
| 0 to 4 | Single-clock risk. Map every carrier window before changing anything else, then consider outside support. |
When should a practice consider outside billing support?
Outside help makes sense when the in-house approach has reached its limits and denials keep returning despite steady effort. The signals below are common in practice, and any three of them together usually justify a closer look at outside support, even if a capable biller is already on staff:
- A CO-29 rate above 1% on any carrier or line for two months in a row.
- Claims regularly leaving the office after day 60 of a 120-day window.
- No one owns rejection work, and acceptance reports are not saved.
- Medicaid, Medicare Advantage and commercial Blue claims share one flat alert.
- Corrected claims are tracked from the wrong date or not tracked at all.
When choosing a billing partner, look for a US-based team, carrier-level deadline mapping, written escalation steps for late claims, and reporting that separates carriers instead of blending them. Ask how the team proves timely filing and who handles reconsideration requests.
EON MED SOLUTIONS is one example. The company provides end-to-end medical billing, coding, credentialing, denial management and compliance support through a US-based team with transparent reporting. Review the medical billing, credentialing and RCM services to see how that process works. Results vary by practice.
Expert Opinion
The bottom line on the BCBS New York timely filing limit is that the card name does not decide the deadline; the carrier, the line of business and the agreement do. A practice that maps each Blue carrier to its own window, saves acceptance reports and counts corrected claims on the right clock seldom needs the reconsideration path.
Some numbers here are firm. The 120-day default, the 90-day Medicaid contract floor, the 365-day outer limit for reconsideration and the 25% reduction cap come from New York statute. The carrier windows come from published notices, manuals and policies that vary in age. The 5-business-day target, the 1% CO-29 target, the 50/75/90 alerts, the planning timeframes and every dollar figure are practical or illustrative.
The natural next question is which of your Blue contracts sets a shorter window than your peers or the statute suggests. A carrier-by-carrier review of your agreements answers it, and the EON MED SOLUTIONS billing and RCM services team can help you run that review.
Frequently asked questions
What is the timely filing limit for BCBS in New York?
It depends on the carrier. Empire and Excellus publish 120 days for professional commercial claims, Highmark allows 365 days in western and northeastern New York, and Medicaid managed care plans can use 90 days. New York law sets a 120-day default for state-regulated plans. Confirm the number in your provider agreement.
What is the Highmark BCBS timely filing limit in western New York?
Highmark requires initial claims within 365 days of the date of service, discharge date or last date of treatment, counting weekends. Corrected claims must arrive within 15 months (455 days) of the original claim’s finalization date, effective September 1, 2026. Check the current provider manual because policies are updated.
What is the Excellus BlueCross BlueShield timely filing limit?
Excellus publishes a 120-day filing limit for professional providers and refers hospitals to their contracts. Coordination-of-benefits claims start from the primary payer’s payment date. Late claims can go through a Request for Timely Filing Review, which must be sent within 120 days of the remittance.
What is a good timely filing denial rate?
A commonly used practical target is a CO-29 rate under 1% of submitted claims, tracked by carrier and line rather than blended. This is an industry convention, not a payer or legal standard. When any carrier exceeds 1%, review its window, workflow and rejection backlog.
What is a good submission lag for Blue claims?
Many billing teams aim to send claims within 5 business days of the visit. That is a practical target, not a carrier rule. Faster submission leaves room to fix rejections before the shortest window closes, especially on 90-day Medicaid and Medicare Advantage lines.
Can a Blue plan deny a late New York claim?
Yes, but participating providers on state-regulated plans can request reconsideration under §3224-a(h) when an unusual occurrence caused the delay and the practice has a timely filing pattern. The plan may reduce payment by up to 25% and may deny in full after 365 days from the date of service.
Sources and methodology
Research was completed on October 6, 2026. The list below groups each source by type. Results vary by practice, and figures reflect information available at the time of research. Where sources conflict, the article gives the range and names the sources.
(a) Published standards and definitions from named bodies
- New York Insurance Law §3224-a (New York State Senate, current revision).
- Highmark Provider Manual, Chapter 6, Unit 1: General Claim Submission Guidelines (New York timely filing policy), and Highmark provider news on corrected claims (effective September 1, 2026).
- Anthem Blue Cross and Blue Shield New York Medicaid Reimbursement Policy: Claims Timely Filing (April 2026 version) and Highmark Medicaid managed care Claims Timely Filing policy G-06050.
- Empire BlueCross BlueShield provider notice on Medicare Advantage timely filing (July 2019), as reproduced by XiFin, and Anthem provider news on the Empire-to-Anthem name transition (effective January 1, 2024).
- Excellus BlueCross BlueShield Navigating the Blues billing orientation guidebook and Request for Timely Filing Review form.
- BlueCard Program FAQ pages published by Excellus and Highmark.
(b) Named benchmarking data providers
- None used. This article does not rely on proprietary benchmarking data.
(c) Practical or illustrative targets from general industry sources
- The 5-business-day submission target, the 1% CO-29 target, the 50/75/90 alert schedule and the improvement timeframes are commonly used practical targets, not mandates.
- Billing reference sites (Muni Health, MedSole RCM, BellMedEx and others) report one-year, 90-day and 15-month figures for New York Blue plans. These are commonly cited across industry sources, are not confirmed carrier policy for every line, and conflict with carrier documents in places.
- All dollar amounts, claim counts and carrier rates in worked examples are illustrative.
(d) Survey or study data
- None used.


